
Albany draws UC Berkeley faculty and staff, Lawrence Berkeley Lab employees and families who want the schools without the Berkeley price, and almost every purchase is a jumbo loan on a small older home. Because inventory is thin and bidding wars are common, we document income and source of funds fully up front so the pre-approval holds up when an offer needs to move fast. The phone calls we get about a reverse mortgage in Albany usually start with a specific worry: a mortgage payment that is hard to carry on a fixed income, a spouse who needs care at home, a roof that cannot wait, or a wish to stop drawing down savings so quickly. The federally insured HECM program was built for exactly these situations, and a proprietary reverse mortgage may fit higher-value Albany homes. We listen first, run the numbers second and let the homeowner and family decide at their own pace.
Call Pacific National Lending for a reverse mortgage in Albany: (916) 526-2700
Get Pre-approved
Sitting just north of Berkeley between San Pablo Avenue and the I-80 and I-580 interchange, Albany is a small city of about one square mile known for its Solano Avenue shops and restaurants, Albany Hill and its well-regarded schools. We help Albany buyers and homeowners with purchase financing, refinances and home equity lines. To qualify for a reverse mortgage in Albany, the youngest borrower must be at least 62, the home must be your primary residence and you need enough equity to pay off any existing mortgage from the proceeds. Lenders also verify that you can keep paying property taxes, homeowners insurance and any HOA dues.
Get Pre-approved
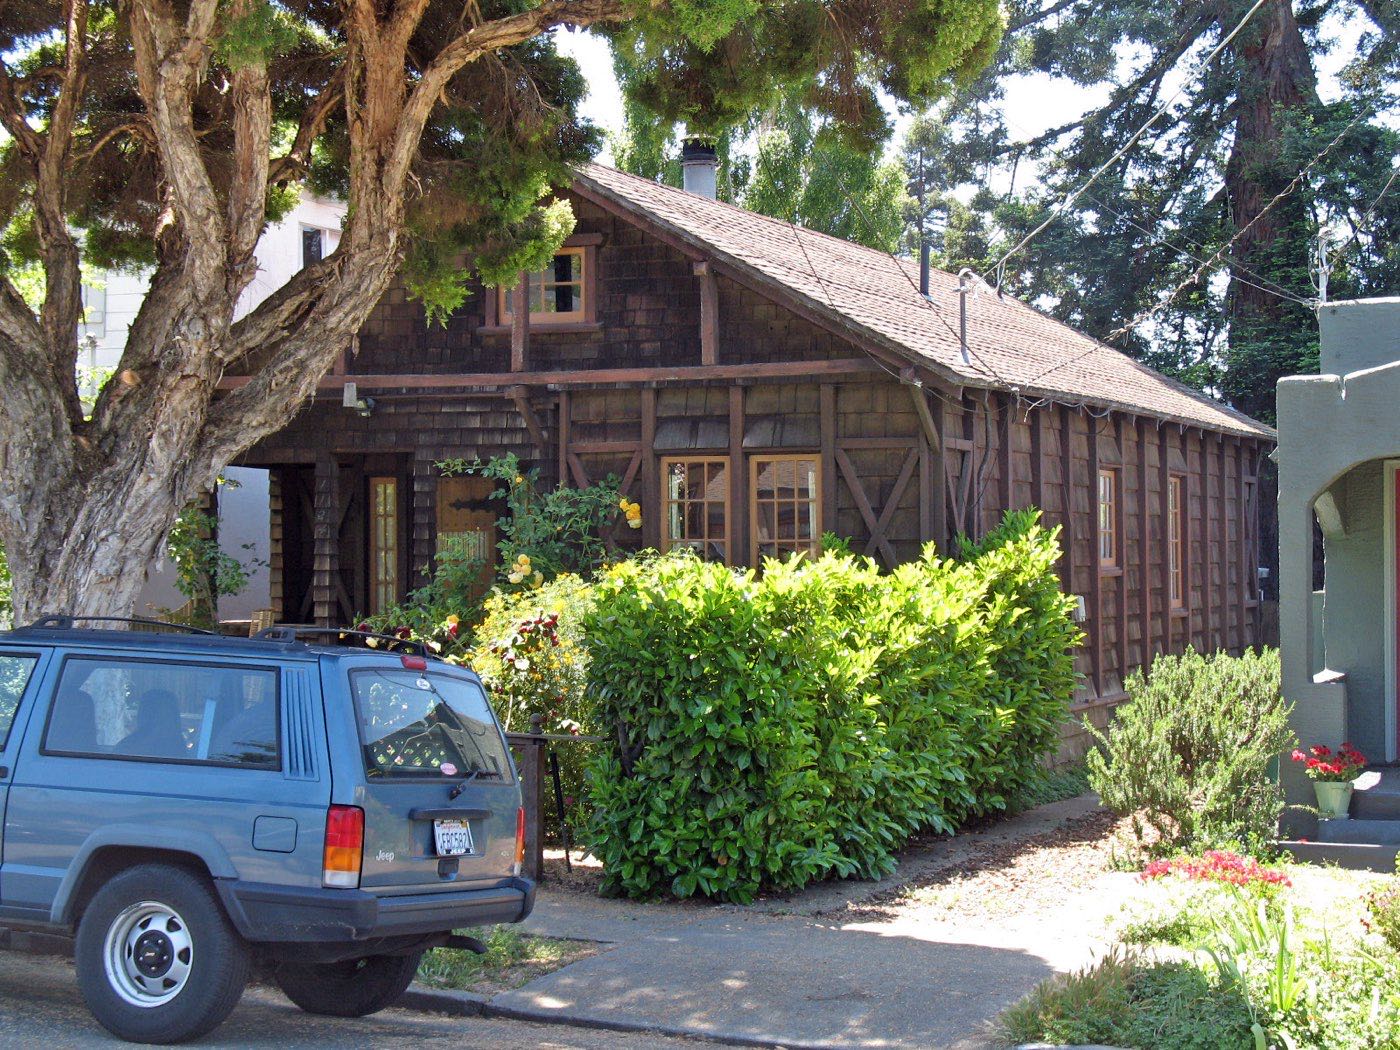
Housing is mostly 1920s to 1940s stucco bungalows and small two-story homes on narrow lots, with a few condos and apartments along San Pablo Avenue and the UC Berkeley family housing at University Village. Proceeds from an Albany reverse mortgage can be taken as a lump sum, monthly payments, a growing line of credit or a combination. Many homeowners choose the line of credit, which grows over time and can be tapped as needed without a monthly payment.
We counsel a Albany homeowner on a reverse mortgage the same way we counsel anyone else: start with the goal. Then we put the reverse mortgage next to the alternatives, a conventional refinance, a HELOC, downsizing, and show what each one costs and delivers over the years you expect to stay. The right answer is whichever fits the goal, and sometimes it is not the reverse mortgage.
Whether you are in Solano Avenue, Albany Hill, University Village, San Pablo Avenue corridor or elsewhere in Albany, the process for a reverse mortgage is the same: one loan officer, clear numbers and a lender chosen to fit your file. Albany is about a two-hour drive from Gold River, and we work with our East Bay clients remotely from the first call through closing using phone, email and electronic signatures.
The quickest way to find out what a reverse mortgage would look like for your Albany situation is a ten-minute call to (916) 526-2700. Prefer to type? The short form on this page reaches the same loan officers.
Get Pre-approvedLearn more about the program itself: Reverse Mortgage · All loan options · Purchase · Refinance · Today's rates
Area photo: "Peterson House (Albany, CA)" by Sanfranman59, CC BY-SA 3.0.
Always. Depending on what you want to accomplish, a conventional refinance, a home equity line or simply staying put may serve you better. We lay out the reverse mortgage beside those alternatives with the costs and the long-term effect on your equity, and we are glad to include your family in the conversation.
Yes. A reverse mortgage is a loan secured by the home, like any mortgage, and the title stays in your name. The lender does not take ownership. You remain responsible for property taxes, homeowners insurance, any HOA dues and keeping the Albany home in good repair, and you can sell or refinance at any time, paying off the balance from the proceeds just as you would with a traditional loan.
There are no restrictions on how proceeds are spent once any existing mortgage on the Albany home is paid off at closing, which is required. Homeowners commonly use the funds to eliminate a monthly payment, pay for in-home care or medical bills, complete repairs or accessibility upgrades, help family or hold a reserve. Because proceeds are loan advances rather than income, they are generally not taxable, though you should confirm your situation with a tax professional.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.