
San Leandro is one of the more attainable owner-occupied markets in the inner East Bay, so first-time buyers, multi-generational families and buyers priced out of Oakland and Alameda make up much of the demand. Many of these purchases fit within FHA and conventional limits, and we run each file as FHA, conventional and VA, add down payment assistance or gift funds where they help, and show the buyer the real monthly difference between the options. The FHA loan program exists to make homeownership reachable for buyers who do not fit the conventional mold, and in San Leandro that describes a lot of households. The government insures the lender against loss, which is why FHA lenders can accept a 3.5 percent down payment, lower credit scores and higher monthly debt loads than a conventional loan would allow. Pacific National Lending works with several FHA-approved lenders, and each applies the FHA rules a little differently, so where a San Leandro file is placed matters.
Call Pacific National Lending for FHA loans in San Leandro: (916) 526-2700
Get Pre-approved
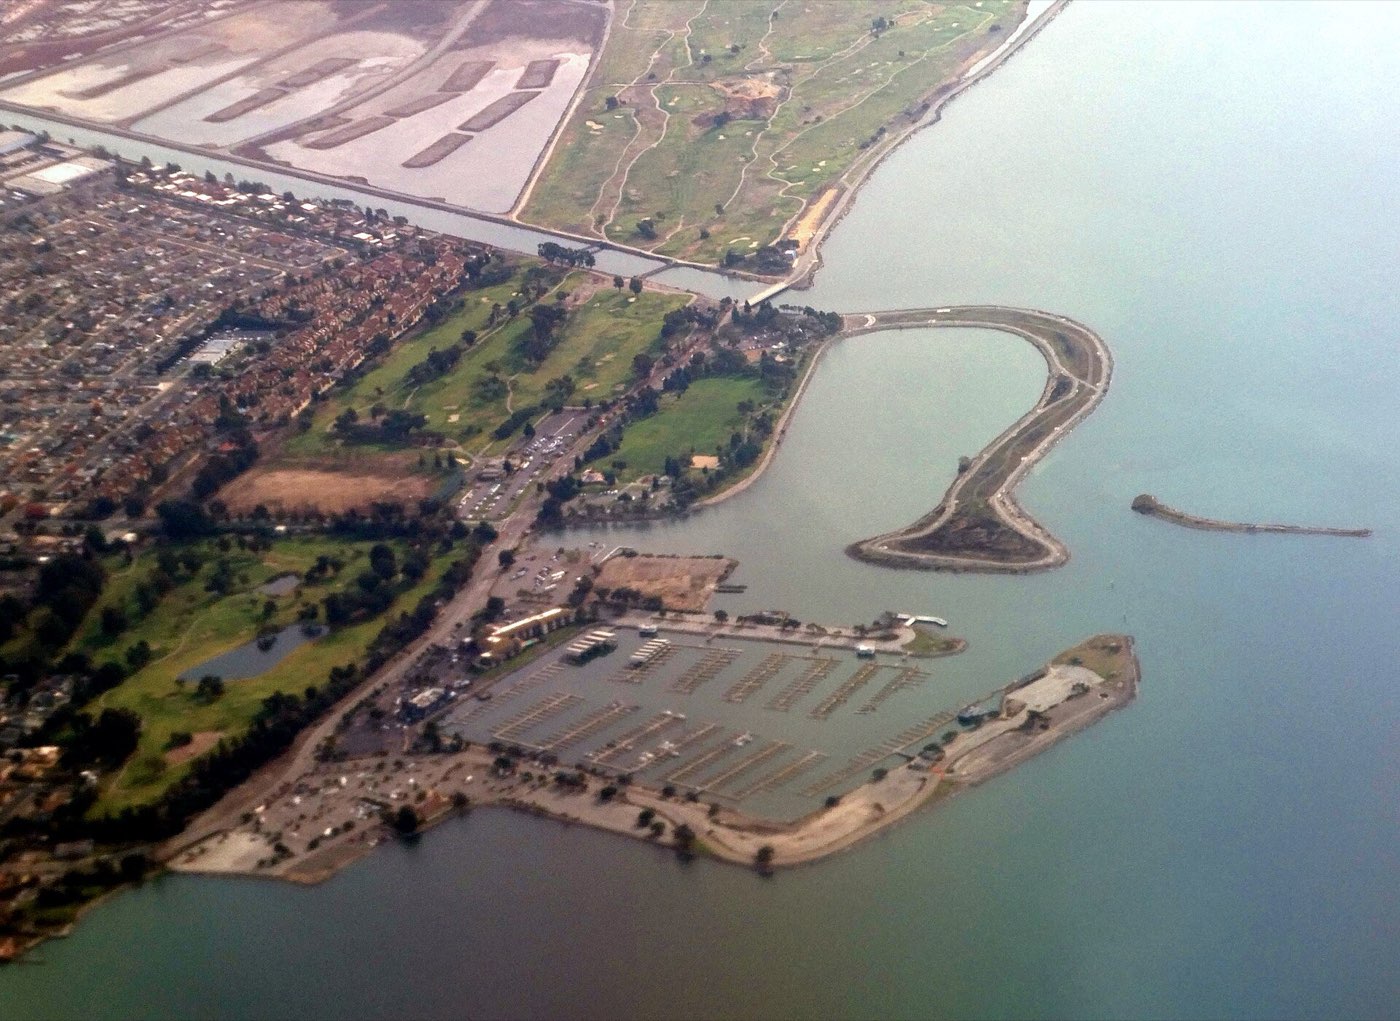
San Leandro stretches from the bay shoreline and San Leandro Marina to the base of the East Bay hills south of Oakland, served by I-880, I-580 and the San Leandro and Bay Fair BART stations, with Bayfair Center and a historic downtown along East 14th Street. We help San Leandro buyers and homeowners with FHA, VA and conventional purchase loans, refinances and equity financing. FHA loan limits are set by county, and in Alameda County they cover most entry-level and mid-range homes in San Leandro. FHA also allows the purchase of 2-to-4-unit properties with 3.5 percent down when you live in one unit, which is a popular strategy for buyers who want rental income to help with the payment.
Get Pre-approved
Housing is mostly 1940s and 50s bungalows and ranch homes in Estudillo Estates, Broadmoor, Washington Manor and Floresta Gardens, hillside homes in Bay-O-Vista, and 1990s and 2000s townhomes and detached homes in Heron Bay and Marina Faire near the shoreline. FHA appraisals in San Leandro include a property condition review, so peeling paint, safety issues or a damaged roof can require repairs before closing. We flag likely issues early and know which lenders and appraisers handle FHA files smoothly, so your San Leandro purchase stays on schedule.
To see whether an FHA loan is right for your San Leandro purchase, call (916) 526-2700 or apply online. We will compare FHA and conventional side by side with actual payment figures, and there is no credit pull at the first step.
San Leandro borrowers in Downtown San Leandro, Estudillo Estates, Broadmoor, Washington Manor and the surrounding neighborhoods work with us for FHA loans because the advice is local and the pricing is shopped. Our Gold River office is about an hour and forty-five minutes from San Leandro, so borrowers there work with us remotely by phone, email and electronic signatures.
The quickest way to find out what FHA loans would look like for your San Leandro situation is a ten-minute call to (916) 526-2700. Prefer to type? The short form on this page reaches the same loan officers.
Get Pre-approvedLearn more about the program itself: FHA Loans · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of San Leandro Marina, December 2023" by Pi.1415926535, CC BY-SA 4.0.
There are two parts: an upfront premium of 1.75 percent of the loan amount that is usually financed into the loan, and an annual premium paid monthly that varies with the loan term, amount and down payment. With less than 10 percent down the monthly premium lasts for the life of the loan. We show San Leandro buyers the exact figure for their scenario.
The appraiser lists the required repairs, and the seller can complete them before closing, the buyer can negotiate a credit, or in some cases a repair escrow allows the work to finish after funding. If the seller refuses, the buyer can walk away under the appraisal contingency. We review San Leandro listings for likely FHA issues ahead of time to avoid this situation.
Yes, as long as you live in one of the units as your primary residence. FHA finances two- to four-unit properties with the same 3.5 percent down payment, and part of the expected rent from the other units can count toward qualifying income, depending on the lender. Loan limits for multi-unit properties in Alameda County are higher than for single-family homes.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.