
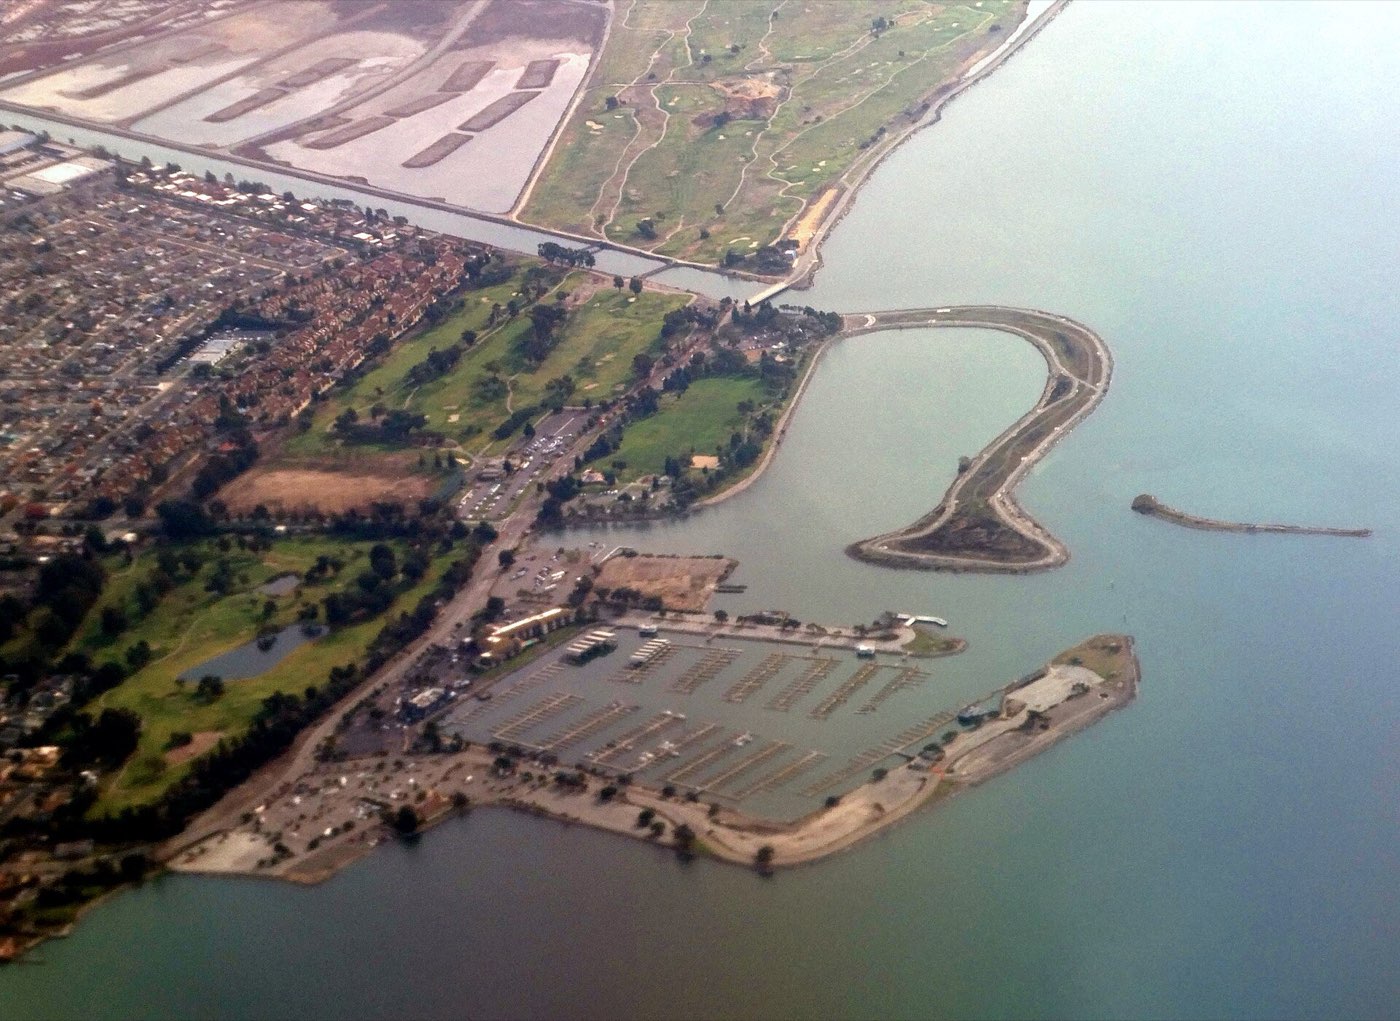
San Leandro stretches from the bay shoreline and San Leandro Marina to the base of the East Bay hills south of Oakland, served by I-880, I-580 and the San Leandro and Bay Fair BART stations, with Bayfair Center and a historic downtown along East 14th Street. We help San Leandro buyers and homeowners with FHA, VA and conventional purchase loans, refinances and equity financing. Once a purchase price in San Leandro pushes the loan amount past the conforming limit for Alameda County, the mortgage leaves the agency-backed market and becomes a jumbo loan held or sold privately by the lender. The practical effect is that no two jumbo programs read the same way. One bank wants twelve months of reserves, another accepts six. One counts restricted stock as income, another does not. Pacific National Lending keeps current guidelines from a wide group of jumbo lenders so an San Leandro borrower is matched to the program that reads their file favorably.
Call Pacific National Lending for jumbo loans in San Leandro: (916) 526-2700
Get Pre-approved
San Leandro is one of the more attainable owner-occupied markets in the inner East Bay, so first-time buyers, multi-generational families and buyers priced out of Oakland and Alameda make up much of the demand. Many of these purchases fit within FHA and conventional limits, and we run each file as FHA, conventional and VA, add down payment assistance or gift funds where they help, and show the buyer the real monthly difference between the options. Because jumbo loans are not sold to Fannie Mae or Freddie Mac, each lender sets its own guidelines. That is exactly why brokering matters in San Leandro: one lender may cap the loan amount or require two appraisals while another prices the same file aggressively with a single appraisal.
Get Pre-approved
Housing is mostly 1940s and 50s bungalows and ranch homes in Estudillo Estates, Broadmoor, Washington Manor and Floresta Gardens, hillside homes in Bay-O-Vista, and 1990s and 2000s townhomes and detached homes in Heron Bay and Marina Faire near the shoreline. Our jumbo process in San Leandro starts with a detailed review of income and assets, because jumbo underwriting asks more questions. A fully underwritten pre-approval from PNL gives listing agents confidence that a large loan will actually close, which matters in competitive offers.
Jumbo files in San Leandro are where thorough documentation pays off. Jumbo lenders want to see income, assets and reserves clearly, and self-employed borrowers can often use bank statements or a single year of returns with the right lender. Because we compare several jumbo investors, a strong file gets priced competitively instead of taking whatever one bank offers.
We help borrowers with jumbo loans throughout San Leandro, including Downtown San Leandro, Estudillo Estates, Broadmoor, Washington Manor, and across the East Bay. Our Gold River office is about an hour and forty-five minutes from San Leandro, so borrowers there work with us remotely by phone, email and electronic signatures.
Ready to talk about jumbo loans in San Leandro? Call (916) 526-2700 or apply online in a few minutes. There is no credit pull at the first step and no obligation.
Get Pre-approvedLearn more about the program itself: Jumbo Loans · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of San Leandro Marina, December 2023" by Pi.1415926535, CC BY-SA 4.0.
Yes, and self-employed borrowers are a large part of the jumbo market in San Leandro. Traditional programs use two years of personal and business tax returns, while alternative programs qualify on a year or two of business or personal bank deposits, CPA-prepared statements or liquid assets. Each approach has different pricing and requirements, and the best fit depends on how your business reports income. We review your returns first and then recommend the path that supports the loan you need.
Reserves are the months of mortgage payments you must still have in verified accounts after the down payment and closing costs are paid. Requirements vary widely by lender and loan size, commonly ranging from six to twelve months and sometimes more on very large loans or second homes. Retirement accounts often count at a discounted value. We confirm the exact reserve requirement for your San Leandro scenario before you commit to a purchase.
It depends on the lender and program. Many jumbo lenders look for 20 percent down, some accept 10 percent with strong credit and reserves, and a few go lower for well-qualified borrowers, usually at a higher rate. Larger down payments generally bring better pricing and fewer conditions. For an San Leandro purchase we price several down payment levels so you can see where the trade-off between cash in and monthly cost makes sense for you.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.