
Union City is a diverse, family-oriented market where many buyers are first-generation homeowners, often with multiple earners on the application or gift funds from relatives, and most detached homes are at or above conventional limits while townhomes and condos remain reachable with FHA or conventional financing. We are careful with pre-approvals here because complex income is common, including self-employment, overtime and rental income, and we document it fully so nothing falls apart in underwriting. Financing a higher-priced home in Union City usually means a jumbo loan, and the difference between lenders on a jumbo file can be significant in both rate and flexibility. As a broker, we shop your jumbo loan across banks, credit unions and non-bank lenders and present the best fit in writing.
Call Pacific National Lending for jumbo loans in Union City: (916) 526-2700
Get Pre-approved
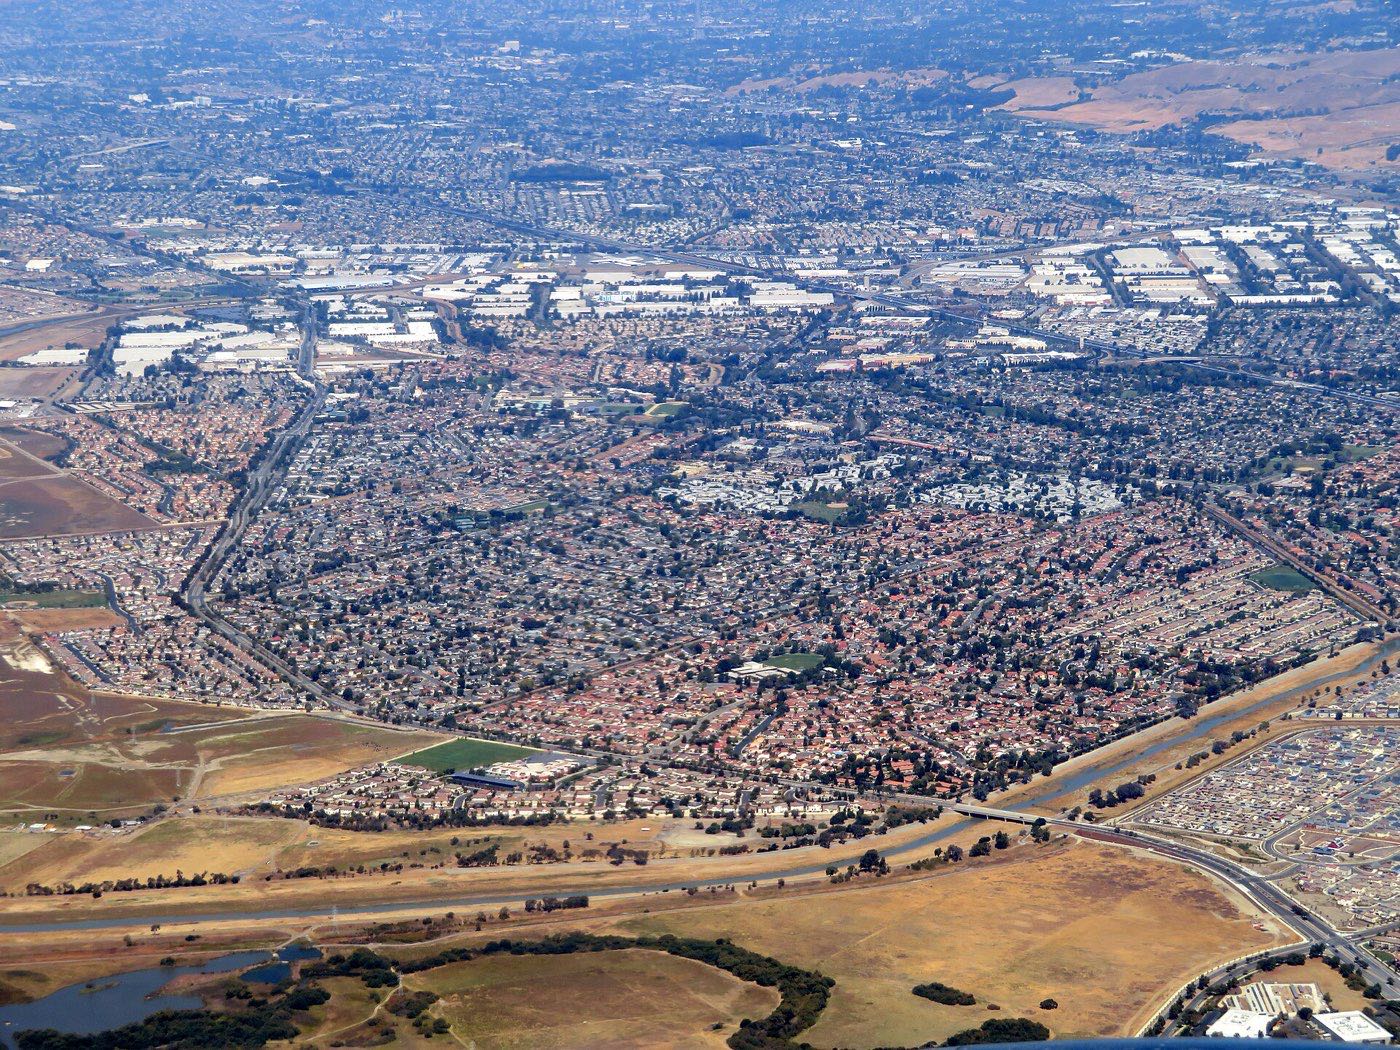
Union City lies between Hayward and Fremont along I-880 and Mission Boulevard, built around the historic Alvarado and Decoto districts, the Union City BART station, the Union Landing shopping center and the trailheads of Dry Creek Pioneer Regional Park. We help Union City buyers and homeowners with purchase loans, refinances, cash-out refinances and home equity lines. Lenders price jumbo loans in Union City on risk, and the inputs are concrete: loan-to-value, credit score, property type, occupancy and whether the loan is a purchase or cash-out refinance. Second homes and condominiums carry adjustments at many lenders, while a primary residence with 25 percent or more down usually sees the best terms. Rather than guessing, we price your exact scenario across our lender list and show how each variable changes the result, so an Union City buyer can decide whether putting more down or restructuring the loan is worth it.
Get Pre-approved
Housing includes 1950s and 60s homes in old Alvarado and Decoto, 1970s to 90s subdivisions off Alvarado-Niles Road and Dyer Street, hillside homes in Seven Hills near Mission Boulevard, and new townhomes and apartments in the Station District around BART. Conforming loan limits vary by county, and in some higher-cost counties a high-balance conforming loan reaches well above the national baseline. Depending on where the loan amount for an Union City purchase lands relative to the Alameda County limit, it may be possible to structure the financing either as high-balance conforming or as jumbo. The two are priced and underwritten differently, and the better choice shifts with the market. Sometimes a jumbo rate wins for a strong borrower; other times a conforming mortgage with a piggyback second or a larger down payment comes out ahead. We run both paths for every Union City file near the line and show the comparison in writing.
Jumbo files in Union City are where thorough documentation pays off. Jumbo lenders want to see income, assets and reserves clearly, and self-employed borrowers can often use bank statements or a single year of returns with the right lender. Because we compare several jumbo investors, a strong file gets priced competitively instead of taking whatever one bank offers.
Whether you are in Alvarado, Decoto, Station District, Union Landing or elsewhere in Union City, the process for jumbo loans is the same: one loan officer, clear numbers and a lender chosen to fit your file. Union City is nearly two hours from our Gold River office, so our clients there handle the loan start to finish by phone, email and secure e-signature.
If you are weighing jumbo loans in Union City, send us the basics through the form below or call (916) 526-2700. You will get a straight answer about what you qualify for and what it would cost, with nothing pulled on your credit until you say so.
Get Pre-approvedLearn more about the program itself: Jumbo Loans · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of Union City, September 2018" by Pi.1415926535, CC BY-SA 3.0.
Yes. Several jumbo lenders accept one year of tax returns or twelve to twenty-four months of bank statements, and some count a portion of liquid assets toward qualifying. Jason is self-employed himself and reads profit and loss statements for a living, so a complicated Union City jumbo file is familiar territory.
Reserves are the months of mortgage payments you must still have in verified accounts after the down payment and closing costs are paid. Requirements vary widely by lender and loan size, commonly ranging from six to twelve months and sometimes more on very large loans or second homes. Retirement accounts often count at a discounted value. We confirm the exact reserve requirement for your Union City scenario before you commit to a purchase.
It depends on the lender and program. Many jumbo lenders look for 20 percent down, some accept 10 percent with strong credit and reserves, and a few go lower for well-qualified borrowers, usually at a higher rate. Larger down payments generally bring better pricing and fewer conditions. For an Union City purchase we price several down payment levels so you can see where the trade-off between cash in and monthly cost makes sense for you.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.