
Union City lies between Hayward and Fremont along I-880 and Mission Boulevard, built around the historic Alvarado and Decoto districts, the Union City BART station, the Union Landing shopping center and the trailheads of Dry Creek Pioneer Regional Park. We help Union City buyers and homeowners with purchase loans, refinances, cash-out refinances and home equity lines. The phrase no income investor loans in Union City covers a family of products rather than a single loan. DSCR loans qualify on the rent the property produces. Bank-statement loans use deposits into a business or personal account over a period of months in place of returns. Asset-based programs qualify on liquid holdings alone. Each has its own pricing and down payment rules, and PNL helps Union City investors pick the one that fits their situation rather than forcing the deal into the wrong box.
Call Pacific National Lending for no income investor loans in Union City: (916) 526-2700
Get Pre-approved
Housing includes 1950s and 60s homes in old Alvarado and Decoto, 1970s to 90s subdivisions off Alvarado-Niles Road and Dyer Street, hillside homes in Seven Hills near Mission Boulevard, and new townhomes and apartments in the Station District around BART. Underwriting a no income investor loan in Union City shifts the questions from the borrower to the deal. Is the rent enough to carry the payment? Is the credit profile solid? Are there reserves to cover a vacancy? Lenders set their own thresholds for each of those, and the required down payment and minimum ratio depend on the lender and the program. Because the borrower's tax situation never enters the file, the approval tends to be more predictable for self-employed investors in Union City than a conventional loan would be.
Get Pre-approved
Union City is a diverse, family-oriented market where many buyers are first-generation homeowners, often with multiple earners on the application or gift funds from relatives, and most detached homes are at or above conventional limits while townhomes and condos remain reachable with FHA or conventional financing. We are careful with pre-approvals here because complex income is common, including self-employment, overtime and rental income, and we document it fully so nothing falls apart in underwriting. Investors in Union City with growing portfolios appreciate that no income loans do not count against the conventional ten-property limit and do not require debt-to-income calculations. We help investors decide when to use conventional financing and when to switch.
Many lenders writing no income investor loans in Union City offer interest-only periods, longer amortizations and adjustable options alongside the standard thirty-year fixed. Those structures change the payment, which changes the ratio, which can change the approval. We model each one before you choose so the Union City deal is built on real numbers.
From Alvarado, Decoto, Station District, Union Landing to the edges of Union City, we have closed loans on the kinds of homes and lots that are typical of the southern East Bay. Union City is nearly two hours from our Gold River office, so our clients there handle the loan start to finish by phone, email and secure e-signature.
If you are weighing no income investor loans in Union City, send us the basics through the form below or call (916) 526-2700. You will get a straight answer about what you qualify for and what it would cost, with nothing pulled on your credit until you say so.
Get Pre-approvedLearn more about the program itself: No Income Investor Loans · All loan options · Purchase · Refinance · Today's rates
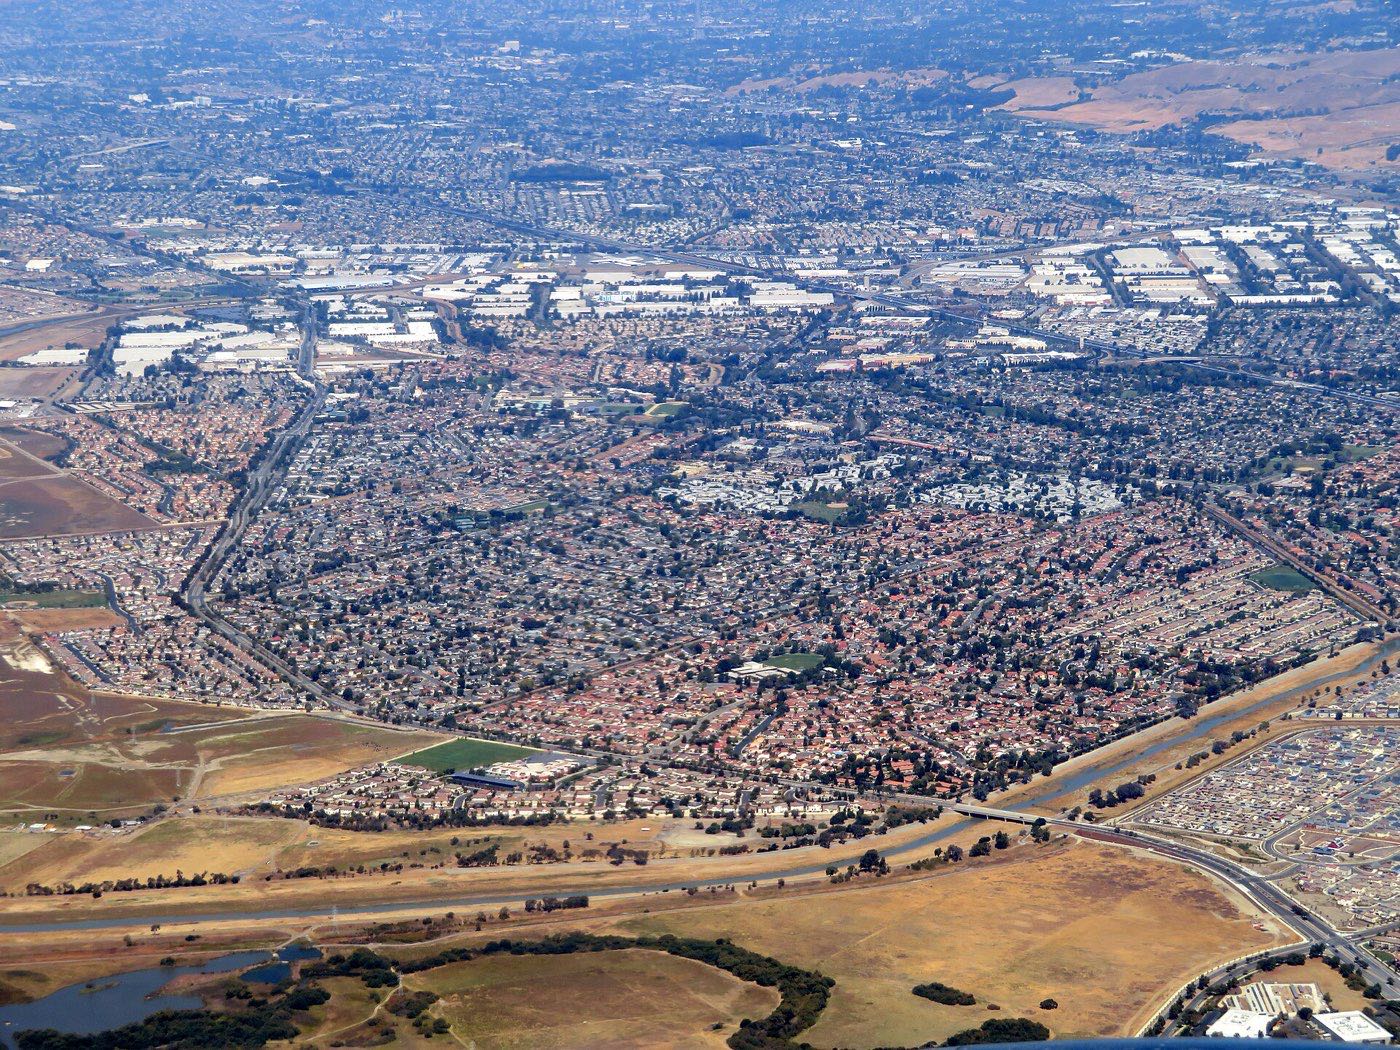
Area photo: "Aerial view of Union City, September 2018" by Pi.1415926535, CC BY-SA 3.0.
It matters more, not less. With no income on the file, credit history is the main evidence of how you handle debt, so lenders set minimum scores and tier their pricing by score. A stronger score can offset a thinner ratio or a smaller down payment on a property in Union City, within whatever limits the lender sets.
In many cases, yes. If you hold a meaningful balance in the bank or in investments that you are not drawing from, several lenders will treat a portion of it as qualifying income even though it sits untouched as your emergency fund. Combined with rental income or a DSCR structure, that opens doors for Union City buyers that a W-2-only lender would keep shut.
Correct in the sense that the lender does not ask for tax returns, W-2s or pay stubs and does not calculate a debt-to-income ratio. The loan still has to make sense, so the lender looks at the property's rent, your credit and your assets instead. The program rules depend on the lender, and Pacific National Lending matches each Union City investor to one whose rules fit.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.