
Union City is a diverse, family-oriented market where many buyers are first-generation homeowners, often with multiple earners on the application or gift funds from relatives, and most detached homes are at or above conventional limits while townhomes and condos remain reachable with FHA or conventional financing. We are careful with pre-approvals here because complex income is common, including self-employment, overtime and rental income, and we document it fully so nothing falls apart in underwriting. The idea that you need 20 percent down to buy a home in Union City keeps a lot of qualified households renting longer than they should. In practice, most purchase loans we broker close with much less. Conventional financing allows 3 percent down for qualifying buyers, FHA requires 3.5 percent, and VA and USDA permit zero down for borrowers who meet their eligibility rules. Pacific National Lending lines these programs up for Union City buyers, explains how each one treats mortgage insurance, and recommends the structure that leaves you with the lowest total cost rather than just the smallest check at closing.
Call Pacific National Lending for low down payment mortgages in Union City: (916) 526-2700
Get Pre-approved
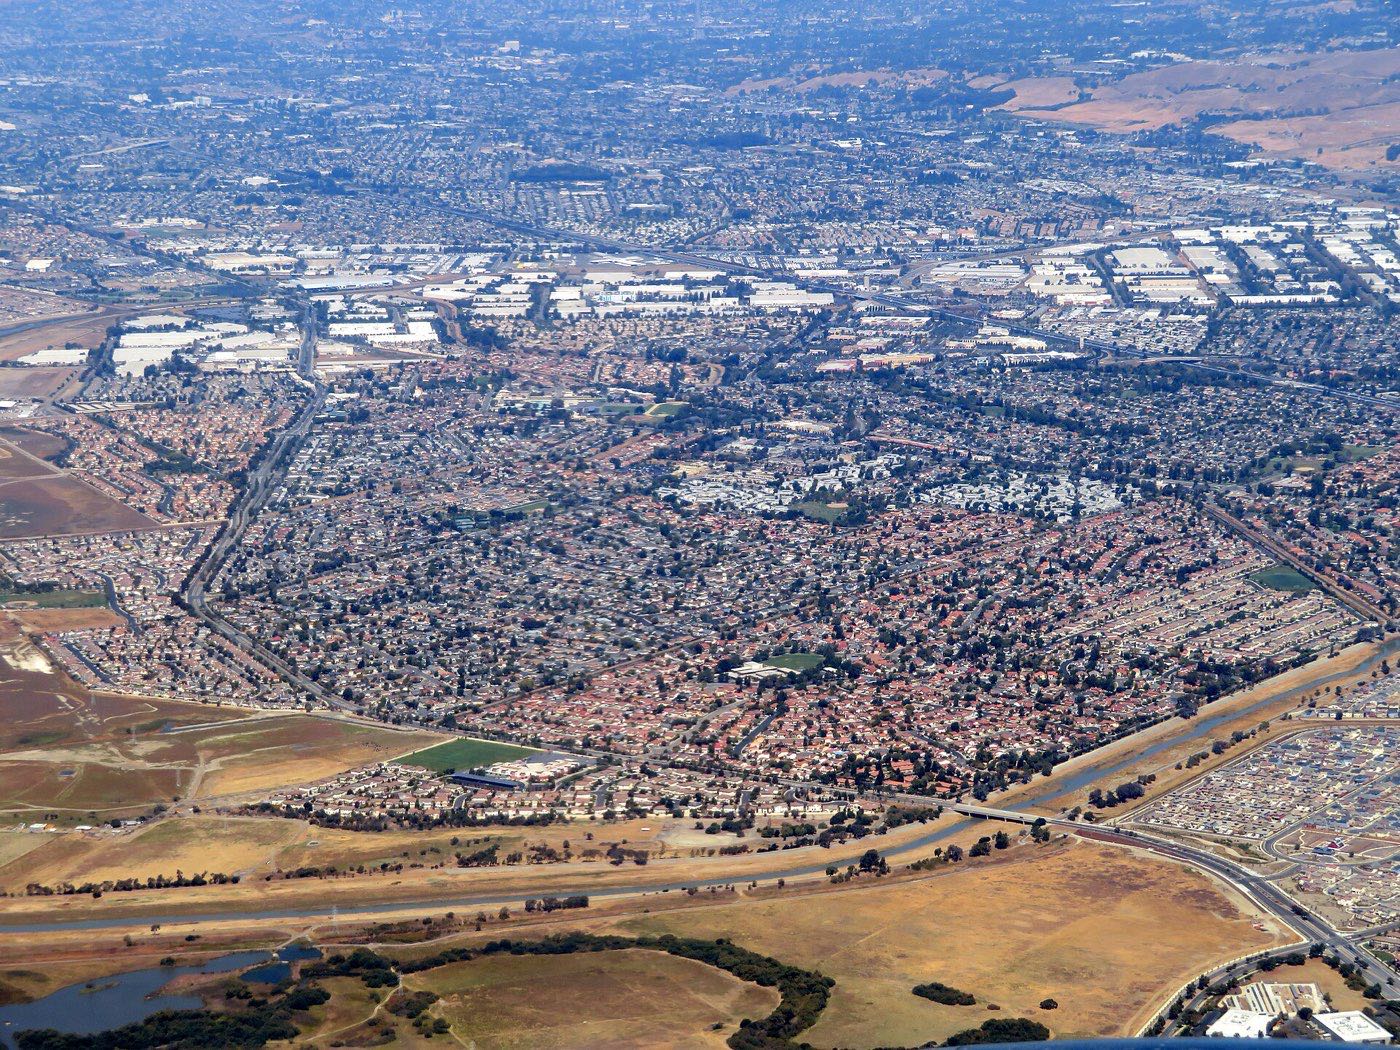
Union City lies between Hayward and Fremont along I-880 and Mission Boulevard, built around the historic Alvarado and Decoto districts, the Union City BART station, the Union Landing shopping center and the trailheads of Dry Creek Pioneer Regional Park. We help Union City buyers and homeowners with purchase loans, refinances, cash-out refinances and home equity lines. FHA's 3.5 percent down loan accepts lower credit scores and higher debt ratios than conventional programs, which makes it the right low down payment choice for many Union City buyers. VA offers zero down for eligible military borrowers, and USDA offers zero down in eligible rural and suburban parts of Alameda County.
Get Pre-approved
Housing includes 1950s and 60s homes in old Alvarado and Decoto, 1970s to 90s subdivisions off Alvarado-Niles Road and Dyer Street, hillside homes in Seven Hills near Mission Boulevard, and new townhomes and apartments in the Station District around BART. Buying in Union City with a small down payment means mortgage insurance for a while, and we plan for its removal from day one. Conventional PMI drops off automatically as equity builds, and FHA loans can be refinanced into conventional loans once the home has appreciated.
Condos and townhomes are a common first purchase in Union City, and low down payment programs treat them a little differently. Conventional lenders review the homeowners association budget and owner-occupancy, and FHA requires the project or the unit to meet its own approval rules. Pacific National Lending checks the property early so a Union City buyer does not fall in love with a unit that the chosen program will not finance.
From Alvarado, Decoto, Station District, Union Landing to the edges of Union City, we have closed loans on the kinds of homes and lots that are typical of the southern East Bay. Union City is nearly two hours from our Gold River office, so our clients there handle the loan start to finish by phone, email and secure e-signature.
For low down payment mortgages in Union City, call Pacific National Lending at (916) 526-2700 or use the secure application on this page. A licensed loan officer will follow up within one business day.
Get Pre-approvedLearn more about the program itself: Low Down Payment Mortgage · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of Union City, September 2018" by Pi.1415926535, CC BY-SA 3.0.
Yes, on most programs. Conventional, FHA and VA loans allow gift funds from family members and certain other donors for the down payment and closing costs, though each program has its own rules about who can give and how the transfer is documented. The donor signs a gift letter and the lender traces the funds. We tell Union City buyers exactly what paperwork to gather so the gift does not slow down underwriting.
Two main programs allow zero down: VA loans for eligible veterans, active-duty service members and some surviving spouses, and USDA loans for homes in qualifying rural and suburban areas with household income under the program limit. Whether a specific Union City address qualifies for USDA depends on the current eligibility map. Beyond those, down payment assistance layered on an FHA or conventional loan can bring a Union City buyer's own contribution close to zero, depending on the program.
Usually yes, for two reasons: the loan balance is larger, and mortgage insurance is added until it can be removed. How much more depends on the program, your credit score and the lender. Conventional PMI can drop off as equity builds, while FHA insurance often remains for the life of the loan unless you refinance. Pacific National Lending shows Union City buyers the payment for each program so the difference is clear before you decide.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.