
Newark is a Peninsula commuter market, with Facebook, Stanford and Silicon Valley employees crossing the Dumbarton Bridge in reverse of the old pattern, and most detached homes now require jumbo financing while older townhomes and condos can still fit conventional limits. We compare conventional, jumbo, FHA and VA on every purchase, and many of our Newark buyers use gift funds from family toward the down payment, which the programs allow. For Newark homeowners who locked in a low first-mortgage rate, a HELOC is usually the smartest way to access equity. Instead of refinancing the whole loan at today's rates, you add a second lien only for the amount you need, and Pacific National Lending helps you find the best terms.
Call Pacific National Lending for a home equity line of credit in Newark: (916) 526-2700
Get Pre-approved
Newark is a flat bayside city surrounded by Fremont on three sides, with I-880, the Dumbarton Bridge on Highway 84 to Palo Alto and Menlo Park, NewPark Mall and the marshes of the Don Edwards San Francisco Bay National Wildlife Refuge along its shoreline. We help Newark buyers and homeowners with purchase loans, refinances, cash-out refinances and equity lines. A HELOC in Newark typically includes a 10-year draw period during which you can borrow and repay, followed by a 20-year repayment period. Interest is variable and tied to the prime rate, though some lenders offer fixed-rate lock options on drawn balances.
Get Pre-approved
Housing is largely 1950s to 1970s ranch homes in the Lake Area, Rosemont and Old Town Newark, 1980s and 90s homes in Bridgepointe and Mayhews Landing, and newer townhomes and detached homes in the Sanctuary West and Bayshores developments near the bay. Opening a HELOC in Newark involves an application, a credit report, income documentation and a valuation of the home. For smaller lines some lenders accept a desktop valuation or an exterior inspection instead of a full appraisal, which saves time and money. Once approved you sign the line agreement, wait out the short cancellation window that federal law requires on a primary residence, and then the funds are available. Many Newark homeowners have their line open within a few weeks of applying.
Think of a HELOC on your Newark home as a credit card attached to the house: you pay interest only on what you draw, only while you have it drawn, and you can pay it back and borrow again. If you only need the money for six months until a bonus or an inheritance arrives, a line of credit usually beats a cash-out refinance that would replace a good first-mortgage rate.
Pacific National Lending serves Old Town Newark, Lake Area, Rosemont, Bridgepointe and the rest of Newark for a home equity line of credit. Newark is around two hours from our Gold River office, and we handle the entire process for South Bay clients over the phone, by email and with secure e-signature.
Call Pacific National Lending at (916) 526-2700 or start your application online. We will review your goals, explain your options in plain English and give you real numbers for a home equity line of credit in Newark.
Get Pre-approvedLearn more about the program itself: HELOC · All loan options · Purchase · Refinance · Today's rates
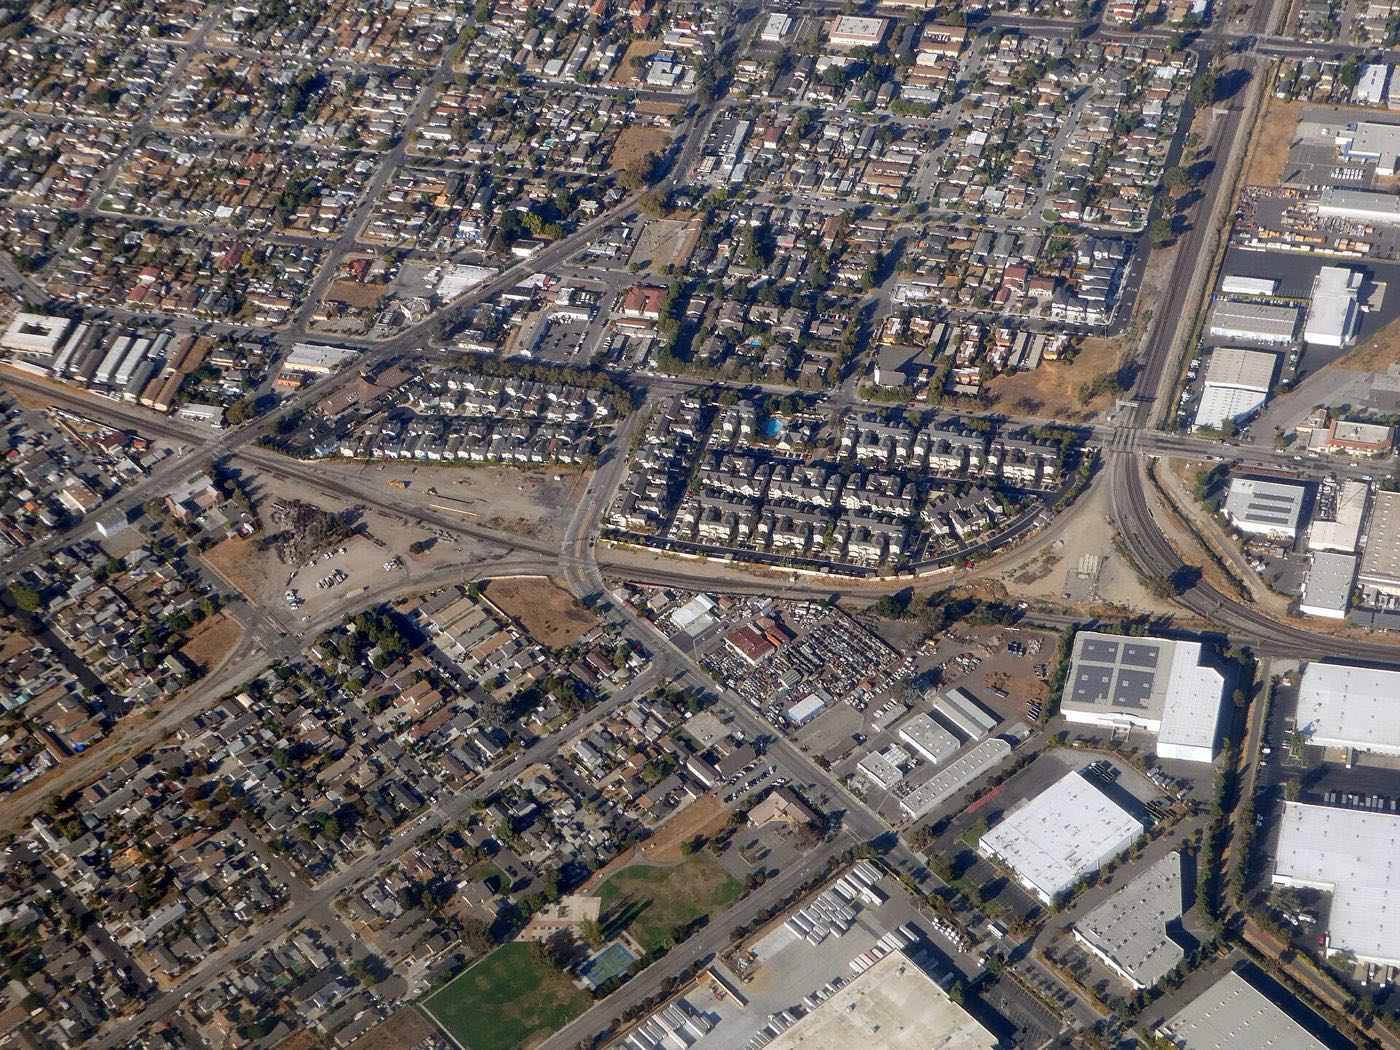
Area photo: "Aerial view of Newark wyes, October 2024" by Pi.1415926535, CC BY-SA 4.0.
If the current market rate is better than the rate on your first mortgage, a cash-out refinance can lower your rate and pull money out at the same time. If your first-mortgage rate is better than today's, leave it alone and use a HELOC so you only pay interest on what you use. We run both options for Newark homeowners, short-term cost and long-term cost side by side.
Yes, though documentation varies. Most lenders ask for tax returns and will average business income over two years. A few offer bank-statement or asset-based lines that do not use returns at all, generally with a lower combined loan-to-value limit. Pacific National Lending knows which lenders take which approach and places self-employed Newark homeowners accordingly.
No. A home equity line of credit is a separate loan recorded as a second lien behind your first mortgage. Your current rate, payment and term stay exactly as they are. The HELOC has its own variable rate and its own payment. That separation is the main reason Newark homeowners with low first-mortgage rates choose a HELOC over a cash-out refinance.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.