
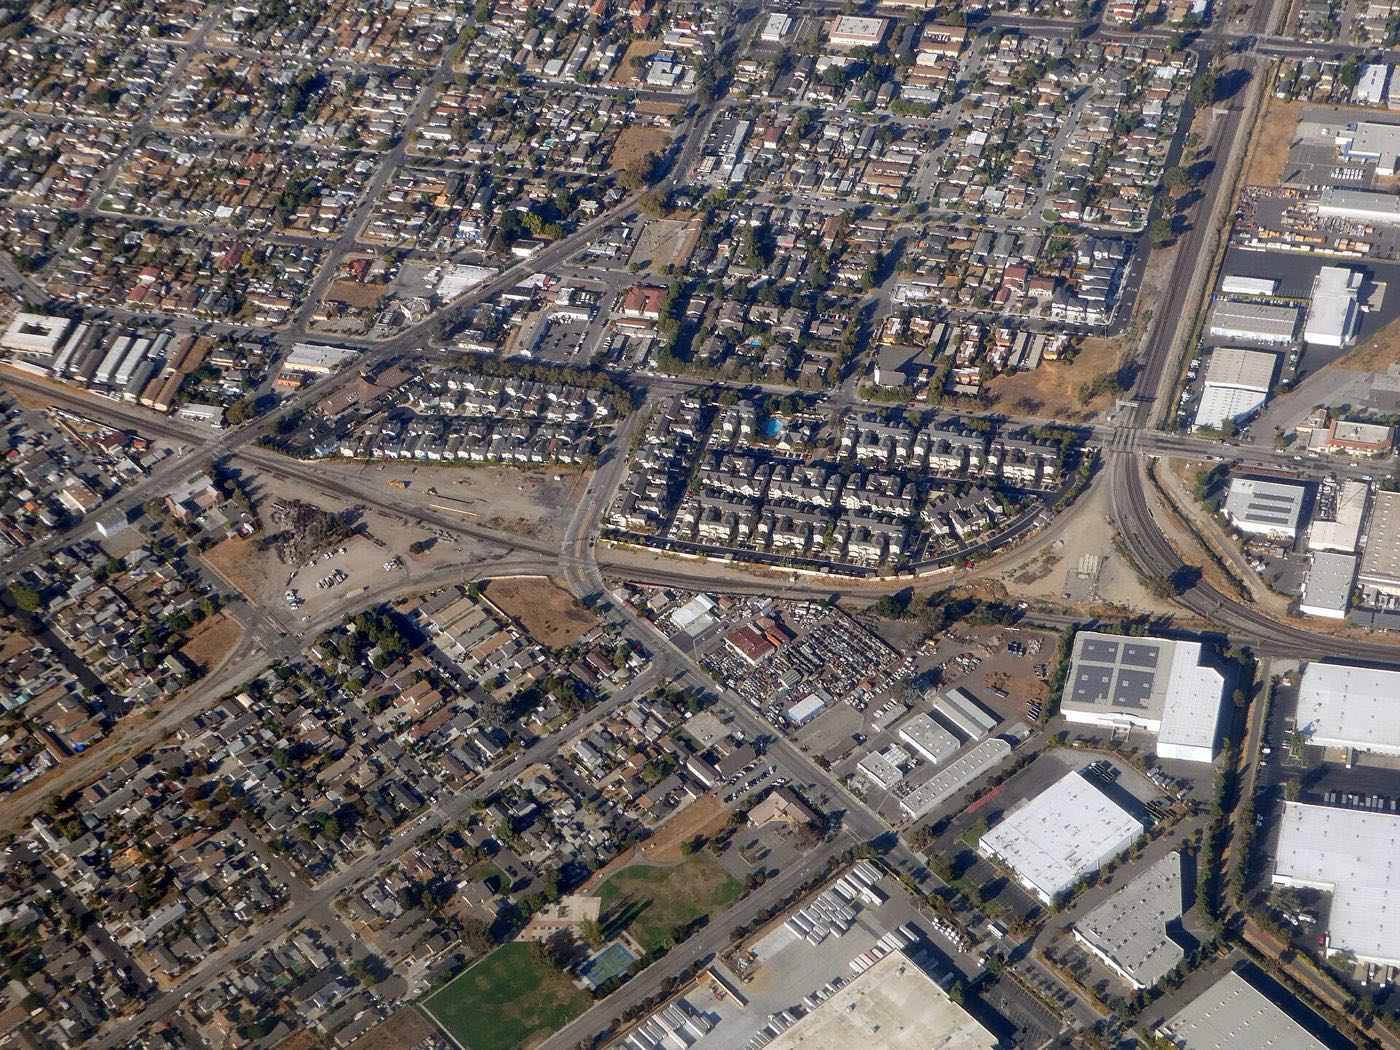
Newark is a flat bayside city surrounded by Fremont on three sides, with I-880, the Dumbarton Bridge on Highway 84 to Palo Alto and Menlo Park, NewPark Mall and the marshes of the Don Edwards San Francisco Bay National Wildlife Refuge along its shoreline. We help Newark buyers and homeowners with purchase loans, refinances, cash-out refinances and equity lines. For many Newark retirees, the home is their largest asset and their largest expense. A reverse mortgage can eliminate the monthly mortgage payment, provide a reserve for medical costs or home repairs, or simply make retirement more comfortable, and the homeowner keeps the title.
Call Pacific National Lending for a reverse mortgage in Newark: (916) 526-2700
Get Pre-approved
Housing is largely 1950s to 1970s ranch homes in the Lake Area, Rosemont and Old Town Newark, 1980s and 90s homes in Bridgepointe and Mayhews Landing, and newer townhomes and detached homes in the Sanctuary West and Bayshores developments near the bay. Qualifying for a reverse mortgage in Newark is less about credit score and more about the home and the household budget. All borrowers must have reached age 62 for a HECM, though a younger spouse can be protected as an eligible non-borrowing spouse, the property must be where you actually live, and it must meet FHA property standards, with repairs sometimes set aside from proceeds. Lenders complete a financial assessment that reviews income, credit history and payment of property charges; if that review raises concerns, part of the loan may be set aside to pay future taxes and insurance rather than the application being declined outright.
Get Pre-approved
Newark is a Peninsula commuter market, with Facebook, Stanford and Silicon Valley employees crossing the Dumbarton Bridge in reverse of the old pattern, and most detached homes now require jumbo financing while older townhomes and condos can still fit conventional limits. We compare conventional, jumbo, FHA and VA on every purchase, and many of our Newark buyers use gift funds from family toward the down payment, which the programs allow. Keeping a reverse mortgage in Newark in good standing comes down to three ongoing duties: pay the property taxes, keep homeowners insurance in force and maintain the home in reasonable condition. The loan also requires that the borrower continue to occupy the property as a primary residence, with annual certification. Extended stays in assisted living beyond twelve months can trigger repayment, which is one reason planning with family matters. We go over these obligations plainly so no Newark homeowner is surprised later.
We counsel a Newark homeowner on a reverse mortgage the same way we counsel anyone else: start with the goal. Then we put the reverse mortgage next to the alternatives, a conventional refinance, a HELOC, downsizing, and show what each one costs and delivers over the years you expect to stay. The right answer is whichever fits the goal, and sometimes it is not the reverse mortgage.
Whether you are in Old Town Newark, Lake Area, Rosemont, Bridgepointe or elsewhere in Newark, the process for a reverse mortgage is the same: one loan officer, clear numbers and a lender chosen to fit your file. Newark is around two hours from our Gold River office, and we handle the entire process for South Bay clients over the phone, by email and with secure e-signature.
Ready to talk about a reverse mortgage in Newark? Call (916) 526-2700 or apply online in a few minutes. There is no credit pull at the first step and no obligation.
Get Pre-approvedLearn more about the program itself: Reverse Mortgage · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of Newark wyes, October 2024" by Pi.1415926535, CC BY-SA 4.0.
The loan comes due when the last borrower passes away or permanently leaves the home. The servicer notifies the estate, and heirs have an initial period, with extensions commonly granted, to decide whether to retire the balance and keep the Newark property or to sell it. Because the loan is non-recourse, neither the estate nor the heirs are responsible for any shortfall if the balance is higher than the sale price.
The loan does not require monthly principal and interest payments, so it cannot go into default for missing those. It can become due if the borrower stops living in the Newark home as a primary residence, lets property taxes or homeowners insurance lapse, or allows the property to fall into serious disrepair. Lenders can set aside funds for taxes and insurance at closing to reduce that risk, and we review each obligation carefully before anyone signs.
Costs include an upfront FHA mortgage insurance premium on a HECM, lender origination charges, an appraisal, title and escrow fees and the counseling session. Most of these can be paid from loan proceeds rather than out of pocket. Interest and ongoing insurance accrue on the balance over time. The total depends on the lender, the program and the Newark home's value, and we provide an itemized estimate so you can compare it against alternatives like a HELOC or downsizing.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.