
Isleton is a small Delta river town on Andrus Island along Highway 160 in the far southern tip of Sacramento County, with a historic Main Street that reflects its Chinese and Japanese cannery-era past. We help Isleton buyers and homeowners with conventional, FHA, USDA and VA loans, financing for older and manufactured homes and refinances. Homeowners in Isleton who are 62 or older often have more wealth in their house than in any account, and a reverse mortgage is one way to put that equity to work without selling or taking on a monthly payment. The borrower stays on title, continues living in the home and remains responsible for property taxes, homeowners insurance and maintenance. Pacific National Lending spends as much time explaining what a reverse mortgage does not do as what it does, because an informed decision is the only kind worth making in Isleton.
Call Pacific National Lending for a reverse mortgage in Isleton: (916) 526-2700
Get Pre-approved
Isleton is USDA-eligible and attracts buyers who want river access and a slow pace at a price far below the rest of Sacramento County, from first-time buyers to retirees and weekend boaters. Nearly everything here sits behind a levee, so flood insurance and flood-zone status are part of every file, and older homes often need an FHA or conventional loan that can handle repairs or an appraisal condition. Qualifying for a reverse mortgage in Isleton is less about credit score and more about the home and the household budget. All borrowers must have reached age 62 for a HECM, though a younger spouse can be protected as an eligible non-borrowing spouse, the property must be where you actually live, and it must meet FHA property standards, with repairs sometimes set aside from proceeds. Lenders complete a financial assessment that reviews income, credit history and payment of property charges; if that review raises concerns, part of the loan may be set aside to pay future taxes and insurance rather than the application being declined outright.
Get Pre-approved
Housing is mostly early 1900s to 1950s homes on and around Main Street, a few 1970s to 90s homes on the edges of town, and manufactured homes and waterfront properties on Andrus and Brannan Islands along the Delta Loop. Keeping a reverse mortgage in Isleton in good standing comes down to three ongoing duties: pay the property taxes, keep homeowners insurance in force and maintain the home in reasonable condition. The loan also requires that the borrower continue to occupy the property as a primary residence, with annual certification. Extended stays in assisted living beyond twelve months can trigger repayment, which is one reason planning with family matters. We go over these obligations plainly so no Isleton homeowner is surprised later.
A HECM line of credit in Isleton has a feature many homeowners do not expect: the unused portion grows each year at the same rate charged on the loan, so a line opened at 65 can be considerably larger at 75. Some retirees open the line early and leave it untouched as a hedge against medical costs or a down market, drawing only if the need arises.
Our a reverse mortgage clients in Isleton come from Main Street historic district, Andrus Island, Brannan Island, Highway 160 corridor and every other part of the Sacramento River Delta. Isleton is about an hour from our Gold River office, and Isleton loans are handled by phone, email and secure e-signature.
The quickest way to find out what a reverse mortgage would look like for your Isleton situation is a ten-minute call to (916) 526-2700. Prefer to type? The short form on this page reaches the same loan officers.
Get Pre-approvedLearn more about the program itself: Reverse Mortgage · All loan options · Purchase · Refinance · Today's rates
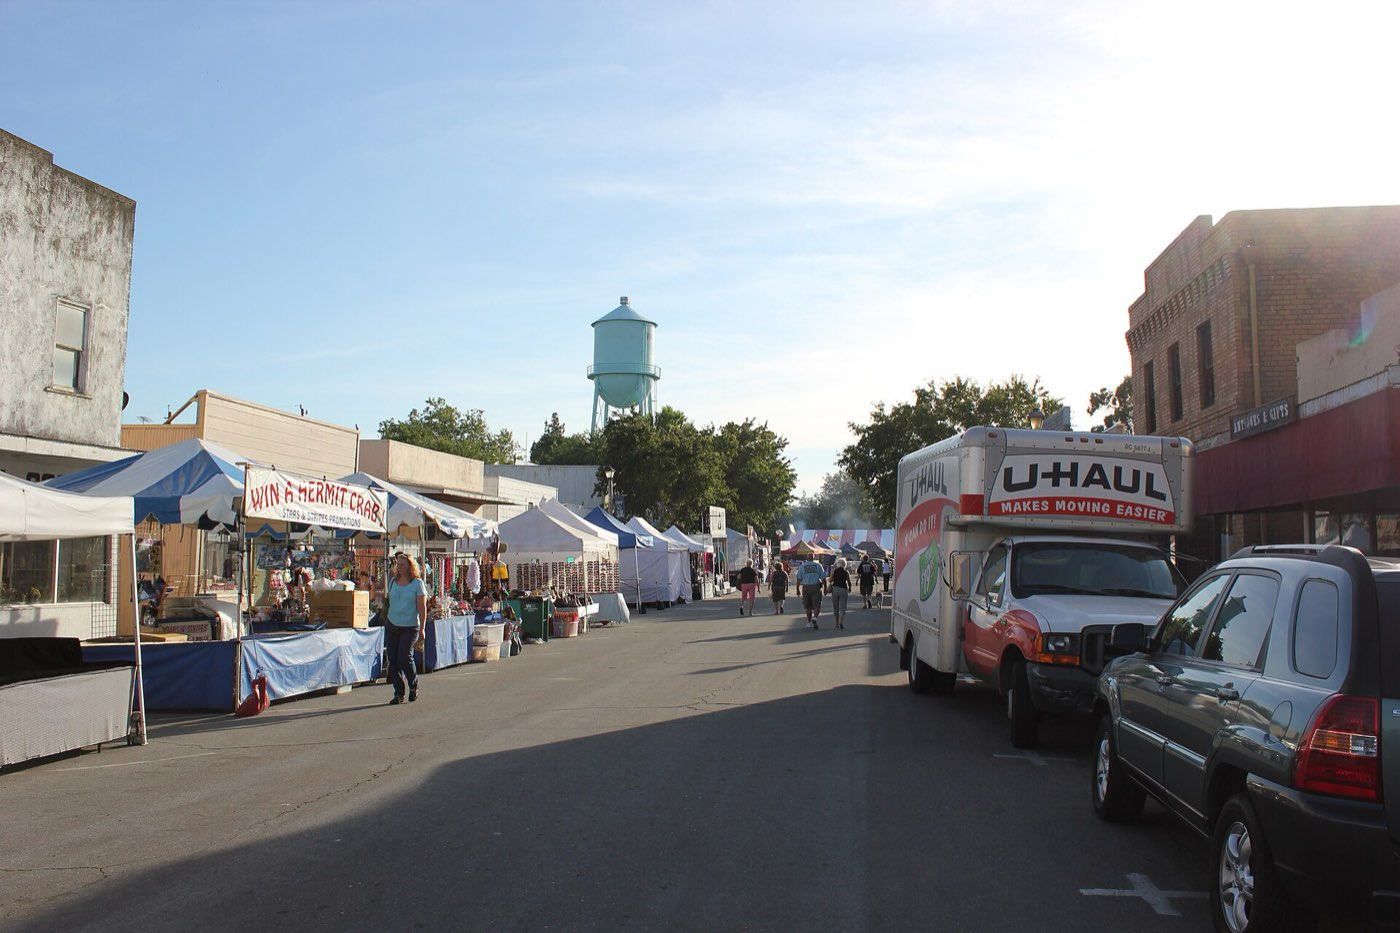
Area photo: "Downtown Isleton (7384115176)" by Eugene Kim from San Francisco, USA, CC BY 2.0.
The loan does not require monthly principal and interest payments, so it cannot go into default for missing those. It can become due if the borrower stops living in the Isleton home as a primary residence, lets property taxes or homeowners insurance lapse, or allows the property to fall into serious disrepair. Lenders can set aside funds for taxes and insurance at closing to reduce that risk, and we review each obligation carefully before anyone signs.
For the FHA-insured HECM, every borrower must be at least 62. A spouse who is younger can be listed as an eligible non-borrowing spouse and may remain in the Isleton home after the borrower passes, provided the loan terms are met. Some proprietary reverse mortgage programs accept borrowers as young as 55, but availability and terms vary by lender, so ask us which programs currently serve California.
Always. Depending on what you want to accomplish, a conventional refinance, a home equity line or simply staying put may serve you better. We lay out the reverse mortgage beside those alternatives with the costs and the long-term effect on your equity, and we are glad to include your family in the conversation.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.