
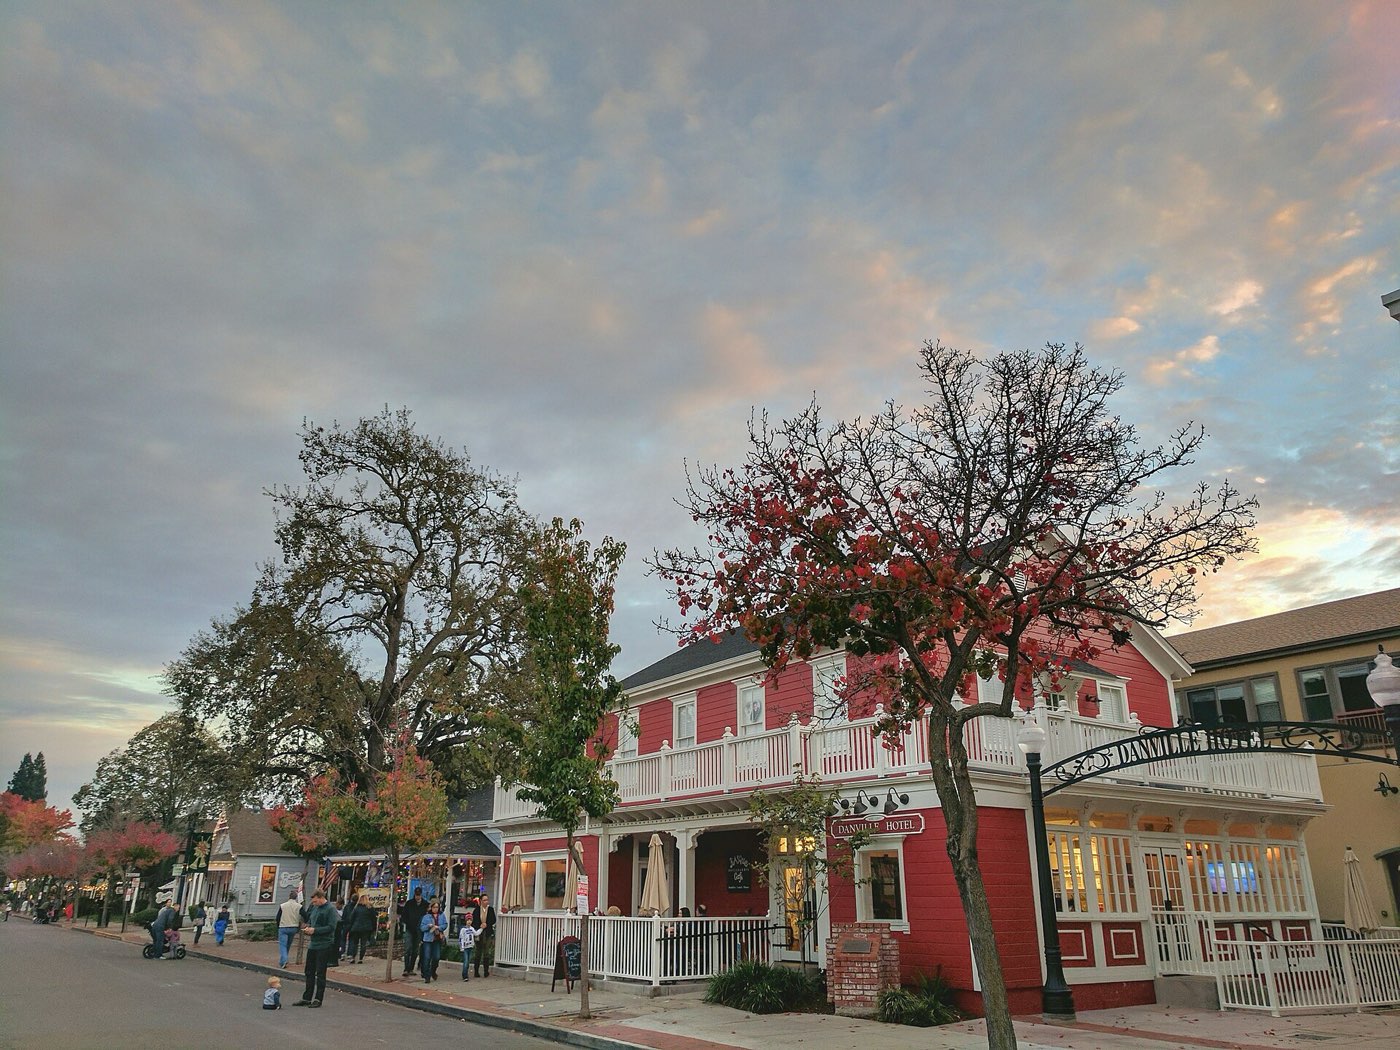
Danville is the heart of the San Ramon Valley along I-680, known for its walkable Hartz Avenue downtown, the Iron Horse Regional Trail, the gated Blackhawk community and the San Ramon Valley Unified schools, with Mount Diablo rising to the east. We help Danville buyers and homeowners with jumbo purchase loans, jumbo refinances, equity lines and reverse mortgages. Homeowners in Danville who bought or refinanced when rates were low face a problem when they need cash: a full refinance would reset the entire balance to a higher rate. A HELOC solves it. You keep the first mortgage, open a line against the equity above it, and pay interest only on what you draw. PNL compares HELOC lenders on rate margin, fees, draw terms and minimum draw requirements, then presents Danville homeowners with a short list and a clear recommendation.
Call Pacific National Lending for a home equity line of credit in Danville: (916) 526-2700
Get Pre-approved
Housing includes 1950s and 60s ranch homes on the Westside and in Sycamore and Greenbrook, 1980s and 90s custom and semi-custom homes in Blackhawk and Magee Ranch, and 2000s homes in the Alamo Creek area toward the Tassajara Valley. How much a lender will extend on a home equity line of credit in Danville comes down to a combined loan-to-value calculation: your first mortgage balance plus the new line, divided by the home's value. Each lender sets its own ceiling for that combined figure, and the ceiling is often lower for investment properties, second homes and borrowers with weaker credit. Income is still verified on most HELOCs, though some lenders offer bank-statement or asset-based lines for self-employed Danville homeowners.
Get Pre-approved
Nearly every Danville purchase is a jumbo loan, and buyers are typically executives, Tri-Valley and San Francisco professionals and relocating families who care about the schools and are often selling another home at the same time. We work through reserves, bridge options and asset-based qualifying for these files, and we compare jumbo pricing across our lender panel because the spread between lenders on a large loan is real money. Our HELOC process in Danville is quick: an application, credit and income review, and a valuation that is often automated for smaller lines. Many HELOCs close in two to three weeks, and you can draw funds as soon as the rescission period ends.
A HELOC on a rental property in Danville is harder to find than one on a primary residence, but a handful of lenders write them with tighter combined loan-to-value limits and higher rates. Because Pacific National Lending works with many lenders, we can usually locate an option for investors who want flexible access to equity in a rental they own in Danville.
Pacific National Lending serves Downtown Danville, Blackhawk, Westside Danville, Sycamore and the rest of Danville for a home equity line of credit. Danville is roughly ninety minutes to two hours from Gold River by I-80 and I-680, and our San Ramon Valley clients complete the process with us by phone, email and e-signature.
Ready to talk about a home equity line of credit in Danville? Call (916) 526-2700 or apply online in a few minutes. There is no credit pull at the first step and no obligation.
Get Pre-approvedLearn more about the program itself: HELOC · All loan options · Purchase · Refinance · Today's rates
Area photo: "Hartz Avenue Danville California" by Danvilleca, CC BY-SA 4.0.
If the current market rate is better than the rate on your first mortgage, a cash-out refinance can lower your rate and pull money out at the same time. If your first-mortgage rate is better than today's, leave it alone and use a HELOC so you only pay interest on what you use. We run both options for Danville homeowners, short-term cost and long-term cost side by side.
The line closes to new borrowing and enters repayment. Your payment switches from interest-only to principal and interest on whatever balance remains, so it typically goes up. The repayment term depends on the lender. Homeowners in Danville who want to avoid that jump can pay the balance down early, refinance the line or open a new one, subject to qualifying.
Yes, though documentation varies. Most lenders ask for tax returns and will average business income over two years. A few offer bank-statement or asset-based lines that do not use returns at all, generally with a lower combined loan-to-value limit. Pacific National Lending knows which lenders take which approach and places self-employed Danville homeowners accordingly.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.