
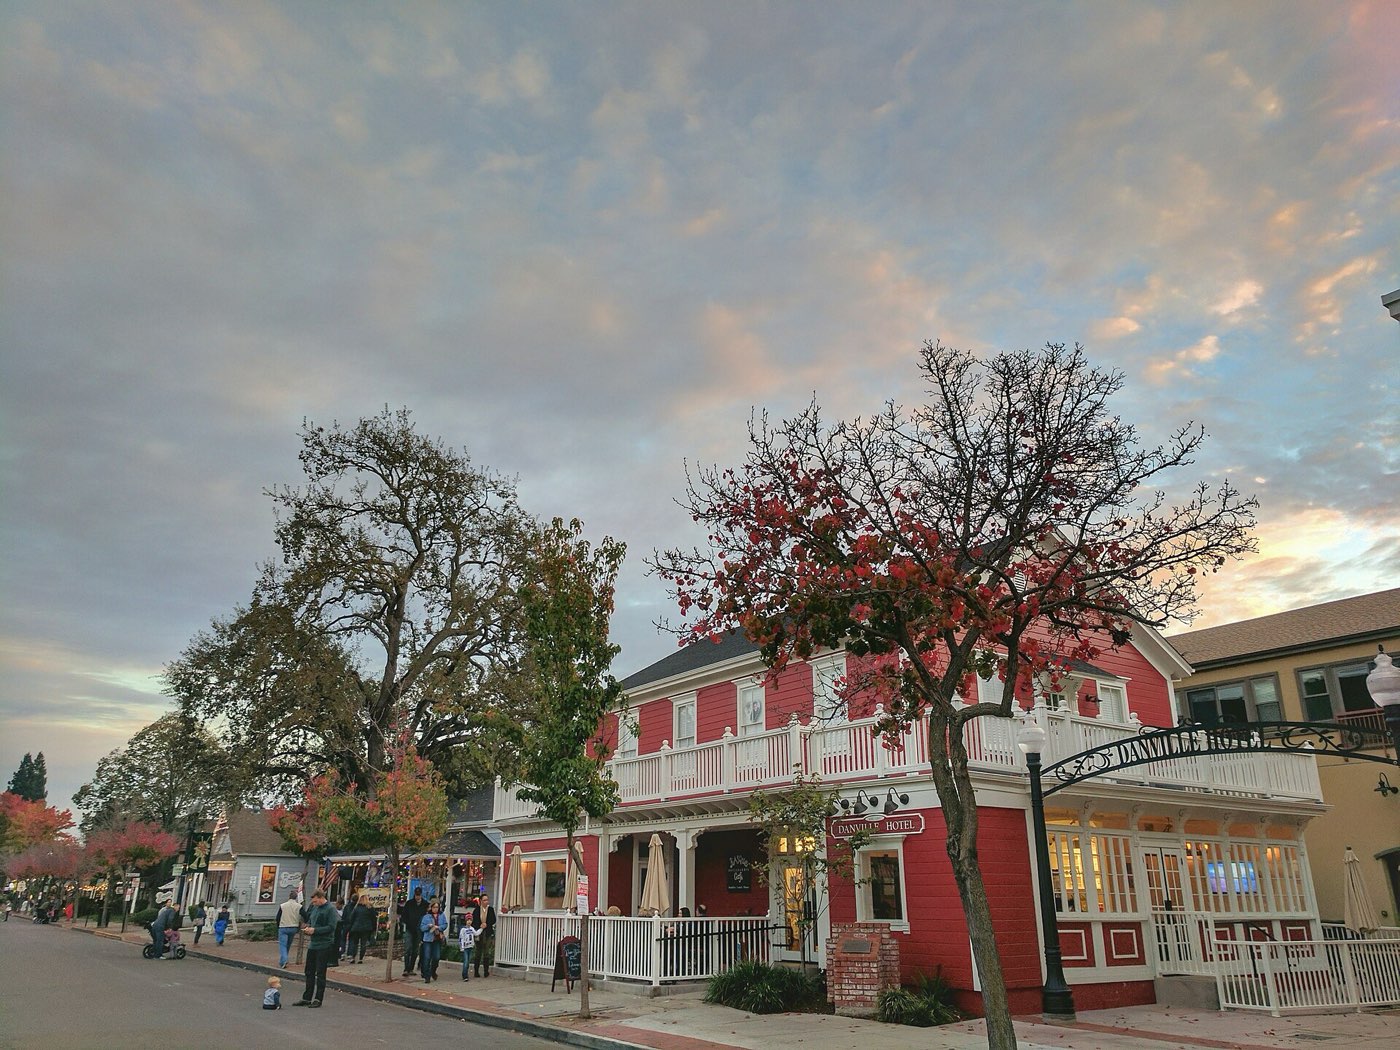
Danville is the heart of the San Ramon Valley along I-680, known for its walkable Hartz Avenue downtown, the Iron Horse Regional Trail, the gated Blackhawk community and the San Ramon Valley Unified schools, with Mount Diablo rising to the east. We help Danville buyers and homeowners with jumbo purchase loans, jumbo refinances, equity lines and reverse mortgages. Shopping for a home loan in Danville means more than finding the lowest advertised rate. Points, lender fees, mortgage insurance and the loan program itself all change what you actually pay, and PNL lays those numbers out side by side so you can make a confident choice.
Call Pacific National Lending for home loans in Danville: (916) 526-2700
Get Pre-approved
Housing includes 1950s and 60s ranch homes on the Westside and in Sycamore and Greenbrook, 1980s and 90s custom and semi-custom homes in Blackhawk and Magee Ranch, and 2000s homes in the Alamo Creek area toward the Tassajara Valley. Where conventional financing ends and jumbo financing begins for a Danville purchase is set by the conforming loan limit in Contra Costa County. Loans at or below and jumbo financing the limit follow Fannie Mae and Freddie Mac guidelines and usually carry the most competitive pricing. Above it, jumbo lenders set their own rules on reserves, credit and documentation, and those rules vary widely. Knowing which side of the line your purchase falls on shapes everything from the down payment to the lender we recommend, so we check it on the first call.
Get Pre-approved
Nearly every Danville purchase is a jumbo loan, and buyers are typically executives, Tri-Valley and San Francisco professionals and relocating families who care about the schools and are often selling another home at the same time. We work through reserves, bridge options and asset-based qualifying for these files, and we compare jumbo pricing across our lender panel because the spread between lenders on a large loan is real money. We have closed home loans on nearly every kind of Danville property, so we know which lenders are comfortable with which homes and how to keep an appraisal or a condition request from delaying your closing. Most purchase loans fund in about three weeks from an accepted offer.
If your credit, income or down payment is not quite where it needs to be, we will tell you exactly what would change the outcome and how long it might take, and then we will keep in touch. Many of our Danville clients started with a plan six months before they bought.
Whether you are in Downtown Danville, Blackhawk, Westside Danville, Sycamore or elsewhere in Danville, the process for home loans is the same: one loan officer, clear numbers and a lender chosen to fit your file. Danville is roughly ninety minutes to two hours from Gold River by I-80 and I-680, and our San Ramon Valley clients complete the process with us by phone, email and e-signature.
Questions about home loans in Danville are what we do all day. Reach Pacific National Lending at (916) 526-2700, or start online and we will call you back with specifics rather than a sales pitch.
Get Pre-approvedLearn more about the program itself: Home Loans · All loan options · Purchase · Refinance · Today's rates
Area photo: "Hartz Avenue Danville California" by Danvilleca, CC BY-SA 4.0.
Minimums vary by program and lender. FHA lenders often accept scores in the 500s with a larger down payment and 580 or above at 3.5 percent down, while conventional loans generally start at 620. A higher score improves pricing on every program. If your score is close to a threshold, we can tell you what would move it before you apply for a Danville purchase.
It depends on the program. Conventional loans allow as little as 3 percent down for qualified buyers, FHA requires 3.5 percent, and VA and USDA loans can be zero down for eligible borrowers. Putting down less usually means paying mortgage insurance or a funding fee, so we compare the monthly cost of each option for your Danville price range before you decide.
Closing costs include lender fees, appraisal, title insurance, escrow charges, recording fees and prepaid items such as property taxes and homeowners insurance. The buyer typically pays them, but sellers in Danville can contribute within program limits, and lender credits can offset some costs in exchange for a slightly higher rate. Your loan estimate lists every item before you commit.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.