
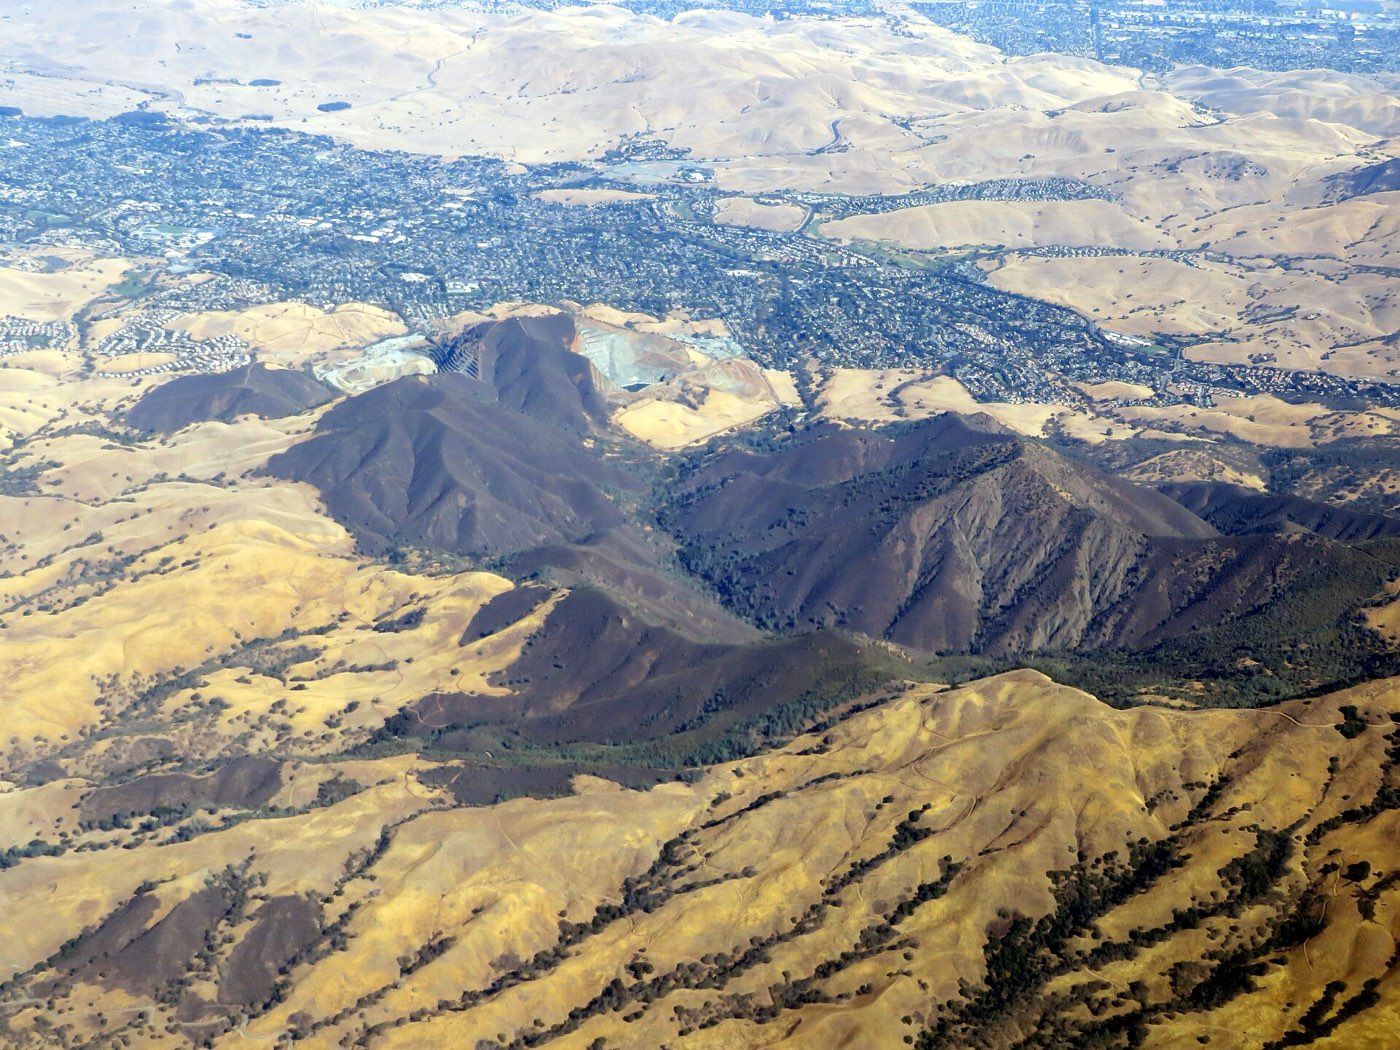
Tucked against the northern base of Mount Diablo at the end of Clayton Road, Clayton is a small town with a historic Main Street downtown, the Oakhurst golf course community and direct access to Mount Diablo State Park and the Marsh Creek Road backcountry. We help Clayton buyers and homeowners with jumbo and conventional purchase loans, refinances and home equity lines. Shopping for a home loan in Clayton means more than finding the lowest advertised rate. Points, lender fees, mortgage insurance and the loan program itself all change what you actually pay, and PNL lays those numbers out side by side so you can make a confident choice.
Call Pacific National Lending for home loans in Clayton: (916) 526-2700
Get Pre-approved
Housing is mostly 1970s and 80s single-family homes in Dana Hills and Regency Woods, 1990s homes in the Oakhurst, Peacock Creek and Eagle Peak subdivisions, and a handful of older homes and ranchettes around the downtown and along Marsh Creek Road. Four things set the rate on a Clayton home loan: your credit score, the size of the down payment relative to the price, the loan amount and the type of property. Improve any one of them and the rate usually improves with it. Sometimes a slightly larger down payment pushes the loan into a better pricing tier, or paying off a small card balance before applying raises the score enough to matter. We run these scenarios for Clayton buyers so the decision rests on numbers rather than guesswork.
Get Pre-approved
Clayton attracts move-up families leaving Concord and Walnut Creek for larger lots, quiet streets and Mount Diablo Elementary, and most detached purchases here are jumbo loans or sit right at the conventional limit, so we price both structures for the buyer. Longtime owners with substantial equity often come to us for HELOCs, cash-out refinances or a reverse mortgage comparison once they retire in place. Our process for Clayton home loans is straightforward: a short application, a document checklist, a fully underwritten pre-approval you can shop with, then appraisal, final approval and closing. You get updates at each step, and one loan officer stays with your file from start to finish.
First-time buyers in Clayton may also qualify for down payment assistance through CalHFA and local programs, which can be layered with FHA or conventional financing to reduce cash to close. We check eligibility for every first-time buyer we work with.
From Downtown Clayton, Oakhurst, Dana Hills, Regency Woods to the edges of Clayton, we have closed loans on the kinds of homes and lots that are typical of the Diablo Valley. Clayton is about ninety minutes from our Gold River office, and we handle files there by phone, email and secure e-signature just as we do for the rest of the East Bay.
Ready to talk about home loans in Clayton? Call (916) 526-2700 or apply online in a few minutes. There is no credit pull at the first step and no obligation.
Get Pre-approvedLearn more about the program itself: Home Loans · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of northwest foothills of Mount Diablo, October 2020" by Pi.1415926535, CC BY-SA 4.0.
Minimums vary by program and lender. FHA lenders often accept scores in the 500s with a larger down payment and 580 or above at 3.5 percent down, while conventional loans generally start at 620. A higher score improves pricing on every program. If your score is close to a threshold, we can tell you what would move it before you apply for a Clayton purchase.
A fixed rate makes sense when you plan to keep the home and the loan for many years and want a payment that never changes. An adjustable loan with a five- or seven-year fixed period can carry a lower starting rate and suits buyers who expect to sell or refinance before it adjusts. We show Clayton buyers both payments and the worst-case adjustment so the choice is informed.
Yes. Self-employed buyers in Clayton qualify for conventional, FHA and VA loans using two years of tax returns, and lenders look at net income after expenses rather than gross receipts. When tax returns understate real cash flow, bank-statement programs from certain lenders can qualify on deposits instead. Which path makes sense depends on the lender and how your business reports its income.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.