
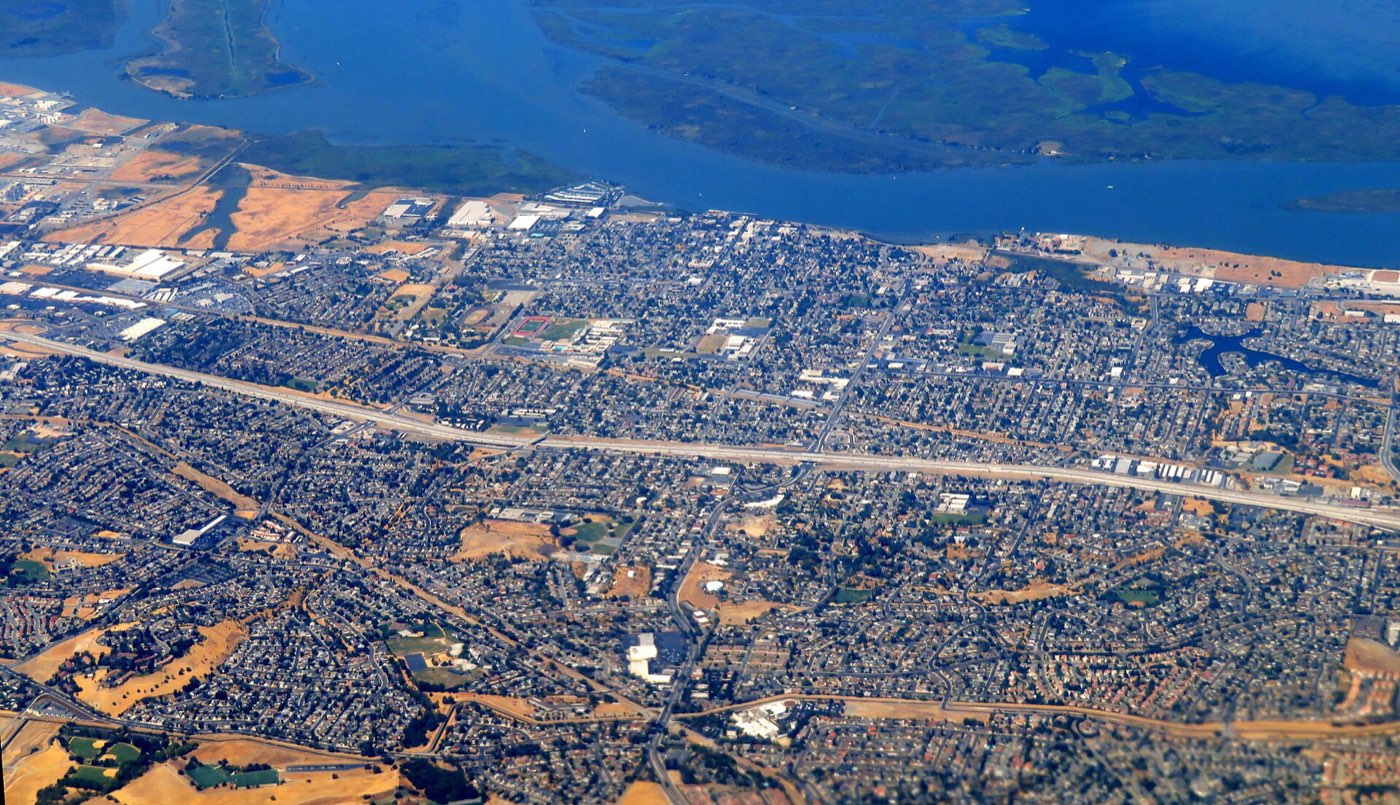
Antioch is the largest city in far east Contra Costa County, sitting on the San Joaquin River Delta along Highway 4 with an Antioch BART station, the Antioch Bridge carrying Highway 160 toward Sacramento, and the Black Diamond Mines Regional Preserve in the hills to the south. We help Antioch buyers and homeowners with FHA, VA and conventional purchase loans, down payment assistance, refinances and equity financing. A home loan in Antioch should fit the property, the budget and the timeline, not the other way around. Our loan officers start by understanding what you are trying to accomplish, then build a financing plan that gets your offer accepted and keeps the monthly payment where you want it.
Call Pacific National Lending for home loans in Antioch: (916) 526-2700
Get Pre-approved
Antioch is where many Bay Area families find a detached home they can actually qualify for, so first-time buyers, FHA and VA borrowers and buyers using down payment assistance or gift funds make up a big part of the market, along with commuters riding BART or Highway 4 toward Concord and Oakland. We run every Antioch file as FHA, conventional and VA and compare the monthly payment and mortgage insurance side by side, and we also help investors who want rental property here with DSCR and conventional investor loans. Where conventional financing ends and jumbo financing begins for a Antioch purchase is set by the conforming loan limit in Contra Costa County. Loans at or below and jumbo financing the limit follow Fannie Mae and Freddie Mac guidelines and usually carry the most competitive pricing. Above it, jumbo lenders set their own rules on reserves, credit and documentation, and those rules vary widely. Knowing which side of the line your purchase falls on shapes everything from the down payment to the lender we recommend, so we check it on the first call.
Get Pre-approved
Housing runs from early-1900s homes in Rivertown near the waterfront to 1970s and 80s homes around Hillcrest and the Contra Loma area and large 1990s and 2000s subdivisions along Lone Tree Way and Deer Valley Road, including Dallas Ranch, Williamson Ranch and Black Diamond Ranch. Because we are based in Gold River, Antioch buyers can lean on us for local knowledge along with financing: which escrow companies close on time, how county loan limits affect the structure, and what sellers and listing agents in this market expect to see in a pre-approval.
A home loan from PNL comes with a fully underwritten pre-approval, transparent pricing across our lender network, and a local team that answers the phone. Call (916) 526-2700 or apply online to see what you qualify for in Antioch.
Our home loans clients in Antioch come from Rivertown, Hillcrest, Deer Valley, Mira Vista Hills and every other part of far east Contra Costa County. Antioch is about an hour and fifteen minutes from Gold River via Highway 160 or Highway 4, and most of our clients there still choose to work with us by phone, email and e-signature.
If you are weighing home loans in Antioch, send us the basics through the form below or call (916) 526-2700. You will get a straight answer about what you qualify for and what it would cost, with nothing pulled on your credit until you say so.
Get Pre-approvedLearn more about the program itself: Home Loans · All loan options · Purchase · Refinance · Today's rates
Area photo: "Antioch aerial view, August 2018 (cropped)" by Pi.1415926535, CC BY-SA 3.0.
It depends on the program. Conventional loans allow as little as 3 percent down for qualified buyers, FHA requires 3.5 percent, and VA and USDA loans can be zero down for eligible borrowers. Putting down less usually means paying mortgage insurance or a funding fee, so we compare the monthly cost of each option for your Antioch price range before you decide.
Yes. Self-employed buyers in Antioch qualify for conventional, FHA and VA loans using two years of tax returns, and lenders look at net income after expenses rather than gross receipts. When tax returns understate real cash flow, bank-statement programs from certain lenders can qualify on deposits instead. Which path makes sense depends on the lender and how your business reports its income.
A fixed rate makes sense when you plan to keep the home and the loan for many years and want a payment that never changes. An adjustable loan with a five- or seven-year fixed period can carry a lower starting rate and suits buyers who expect to sell or refinance before it adjusts. We show Antioch buyers both payments and the worst-case adjustment so the choice is informed.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.