
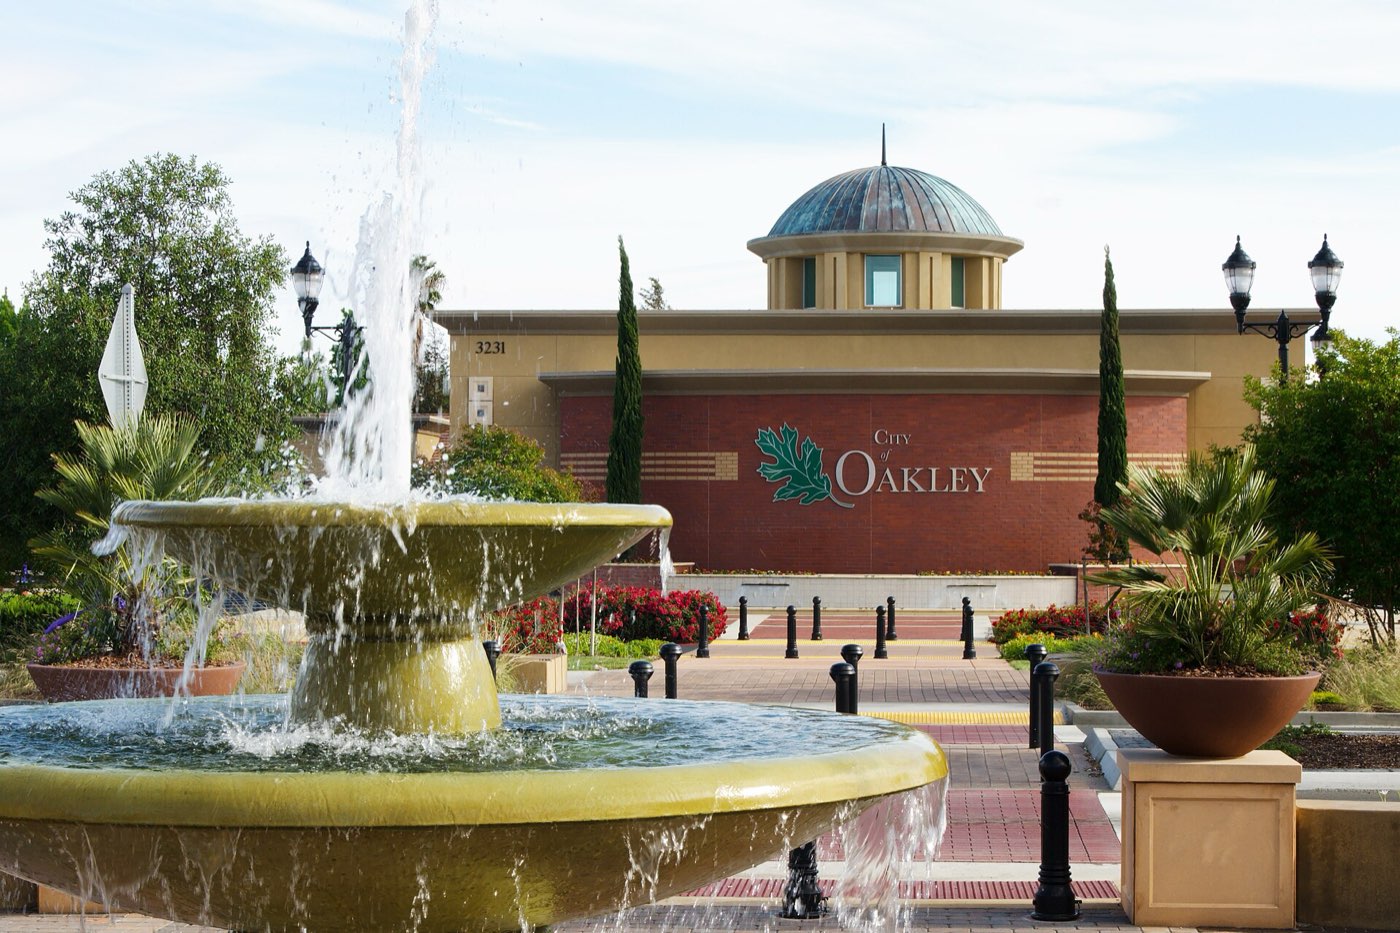
Oakley is a growing Delta town east of Antioch along Highway 4 and Main Street, known for the Big Break Regional Shoreline, its vineyards and new subdivisions, and quick access to Bethel Island and the Delta waterways. We help Oakley buyers and homeowners with FHA, VA, USDA and conventional purchase loans, down payment assistance and refinances. Shopping for a home loan in Oakley means more than finding the lowest advertised rate. Points, lender fees, mortgage insurance and the loan program itself all change what you actually pay, and PNL lays those numbers out side by side so you can make a confident choice.
Call Pacific National Lending for home loans in Oakley: (916) 526-2700
Get Pre-approved
Oakley is one of the few places in Contra Costa County where a first-time buyer can still find a newer detached home within FHA and conventional limits, so FHA, VA and down payment assistance borrowers and families moving out from the inner Bay Area make up most of the market. We check whether a specific address qualifies for USDA zero-down financing, run the file as FHA and conventional alongside it, and compare builder incentives against outside lenders for buyers in the new subdivisions. The loan program that fits an Oakley purchase often depends on the property as much as the borrower. Condos need lender-approved projects, older homes must meet FHA and VA condition standards, and rural parcels may qualify for USDA financing. We check these details before you write an offer, not after.
Get Pre-approved
Housing is mostly 1990s and 2000s subdivisions such as Summer Lake, Cypress Grove, Laurel Woods and Vintage Parkway, newer homes in Emerson Ranch and Delaney Park, and older homes and small ranch properties around downtown Main Street. Buyers in Oakley ask us the same handful of questions, and we would rather answer them early. Yes, you can use gift funds from family for the down payment on most programs. Yes, the seller can pay some or all of your closing costs within program limits. No, you do not have to put 20 percent down to buy, though doing so avoids mortgage insurance on a conventional loan. And yes, a home loan can be structured around a job change or a recent move if the documentation supports it.
A home loan from PNL comes with a fully underwritten pre-approval, transparent pricing across our lender network, and a local team that answers the phone. Call (916) 526-2700 or apply online to see what you qualify for in Oakley.
From Downtown Oakley, Summer Lake, Cypress Grove, Emerson Ranch to the edges of Oakley, we have closed loans on the kinds of homes and lots that are typical of far east Contra Costa County. Oakley is about seventy minutes from Gold River via Highway 160 through the Delta, and clients there work with us by phone, email and e-signature or stop by the office when they are in the Sacramento area.
Call Pacific National Lending at (916) 526-2700 or start your application online. We will review your goals, explain your options in plain English and give you real numbers for home loans in Oakley.
Get Pre-approvedLearn more about the program itself: Home Loans · All loan options · Purchase · Refinance · Today's rates
A fixed rate makes sense when you plan to keep the home and the loan for many years and want a payment that never changes. An adjustable loan with a five- or seven-year fixed period can carry a lower starting rate and suits buyers who expect to sell or refinance before it adjusts. We show Oakley buyers both payments and the worst-case adjustment so the choice is informed.
Closing costs include lender fees, appraisal, title insurance, escrow charges, recording fees and prepaid items such as property taxes and homeowners insurance. The buyer typically pays them, but sellers in Oakley can contribute within program limits, and lender credits can offset some costs in exchange for a slightly higher rate. Your loan estimate lists every item before you commit.
It depends on the program. Conventional loans allow as little as 3 percent down for qualified buyers, FHA requires 3.5 percent, and VA and USDA loans can be zero down for eligible borrowers. Putting down less usually means paying mortgage insurance or a funding fee, so we compare the monthly cost of each option for your Oakley price range before you decide.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.