
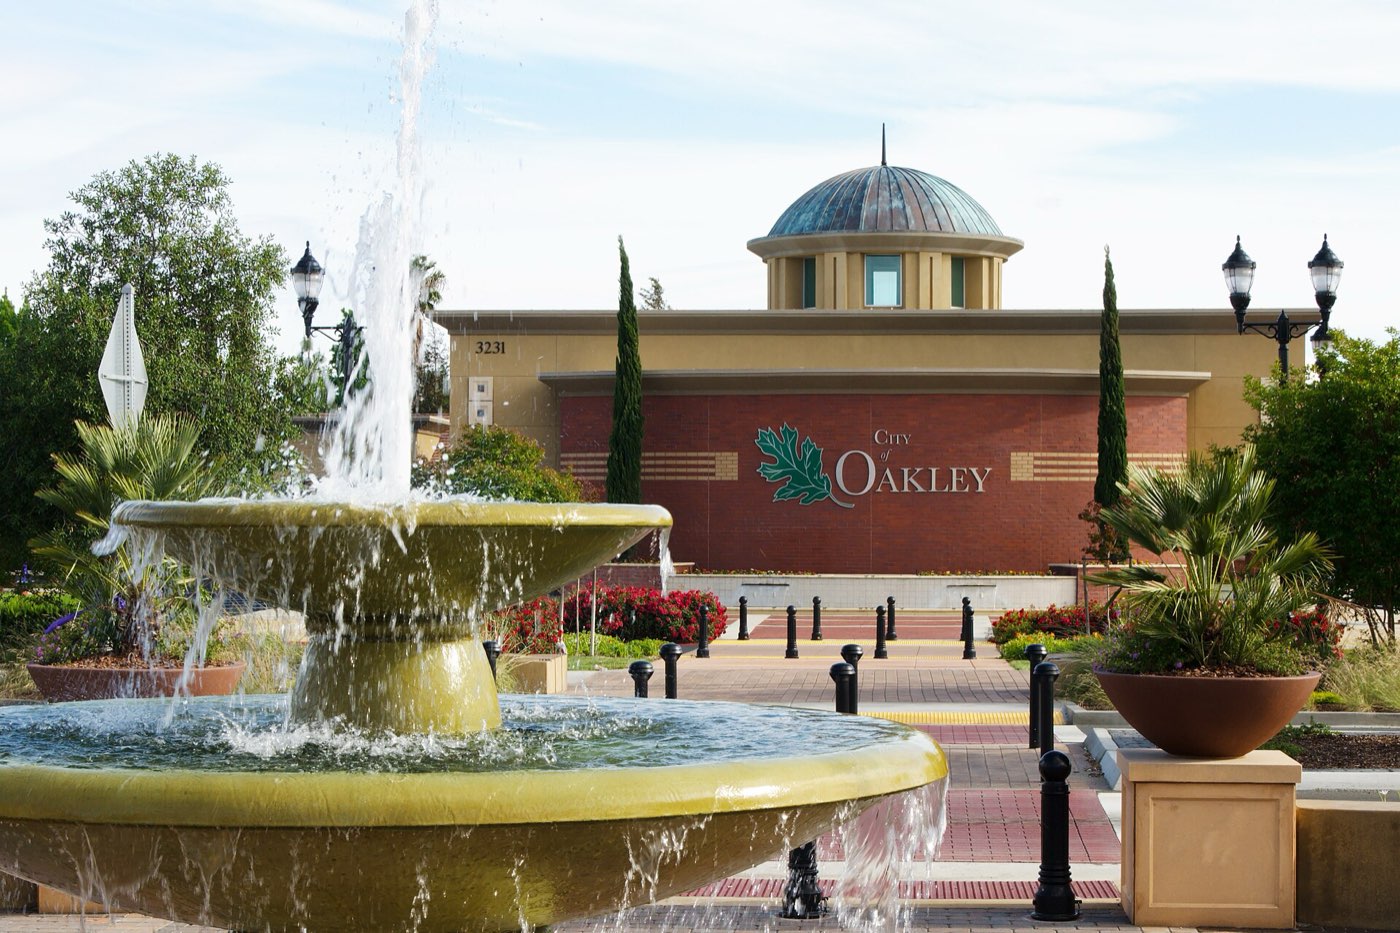
Oakley is one of the few places in Contra Costa County where a first-time buyer can still find a newer detached home within FHA and conventional limits, so FHA, VA and down payment assistance borrowers and families moving out from the inner Bay Area make up most of the market. We check whether a specific address qualifies for USDA zero-down financing, run the file as FHA and conventional alongside it, and compare builder incentives against outside lenders for buyers in the new subdivisions. A common misconception about FHA loans in Oakley is that they are only for buyers with poor credit. In fact, plenty of borrowers with good credit choose FHA because the down payment is small, the qualifying ratios are generous, and the loan can be assumed by a future buyer at the original rate. PNL lays out the complete cost of an FHA loan, including both mortgage insurance premiums, so a Oakley buyer can weigh it against the alternatives honestly.
Call Pacific National Lending for FHA loans in Oakley: (916) 526-2700
Get Pre-approved
Oakley is a growing Delta town east of Antioch along Highway 4 and Main Street, known for the Big Break Regional Shoreline, its vineyards and new subdivisions, and quick access to Bethel Island and the Delta waterways. We help Oakley buyers and homeowners with FHA, VA, USDA and conventional purchase loans, down payment assistance and refinances. FHA loans in Oakley require a minimum 3.5 percent down payment with a 580 or higher credit score, and the down payment can come from savings, a gift from family or an approved down payment assistance program. Sellers can also contribute toward closing costs, which keeps cash to close manageable in this market.
Get Pre-approved
Housing is mostly 1990s and 2000s subdivisions such as Summer Lake, Cypress Grove, Laurel Woods and Vintage Parkway, newer homes in Emerson Ranch and Delaney Park, and older homes and small ranch properties around downtown Main Street. FHA loans are not only for first-time buyers. Move-up buyers, buyers rebuilding credit after a hardship and buyers with student loan debt all use FHA in Oakley, and an FHA loan can later be refinanced into a conventional loan to drop mortgage insurance once equity allows.
FHA loans can be assumed, meaning a future buyer of your Oakley home may be able to take over the loan at its existing rate if they qualify with the lender. In a period of rising rates, that feature can make the home easier to sell. Few conventional loans offer it, and it is one of the quieter advantages of the program.
From Downtown Oakley, Summer Lake, Cypress Grove, Emerson Ranch to the edges of Oakley, we have closed loans on the kinds of homes and lots that are typical of far east Contra Costa County. Oakley is about seventy minutes from Gold River via Highway 160 through the Delta, and clients there work with us by phone, email and e-signature or stop by the office when they are in the Sacramento area.
Ready to talk about FHA loans in Oakley? Call (916) 526-2700 or apply online in a few minutes. There is no credit pull at the first step and no obligation.
Get Pre-approvedLearn more about the program itself: FHA Loans · All loan options · Purchase · Refinance · Today's rates
FHA itself allows scores as low as 580 with 3.5 percent down and 500 to 579 with 10 percent down. Individual lenders often set their own higher minimums, so the practical floor depends on the lender. Because we work with several FHA lenders, a Oakley buyer with a lower score has more places to be considered than at a single bank.
Sometimes. With a strong score a conventional loan with 3 percent down for a first-time buyer, or 5 percent for a repeat buyer, usually beats FHA because the mortgage insurance is cheaper and eventually drops off. Where the score is in the middle, it can go either way, so we run both for every Oakley buyer and show the monthly cost side by side.
The appraiser lists the required repairs, and the seller can complete them before closing, the buyer can negotiate a credit, or in some cases a repair escrow allows the work to finish after funding. If the seller refuses, the buyer can walk away under the appraisal contingency. We review Oakley listings for likely FHA issues ahead of time to avoid this situation.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.