
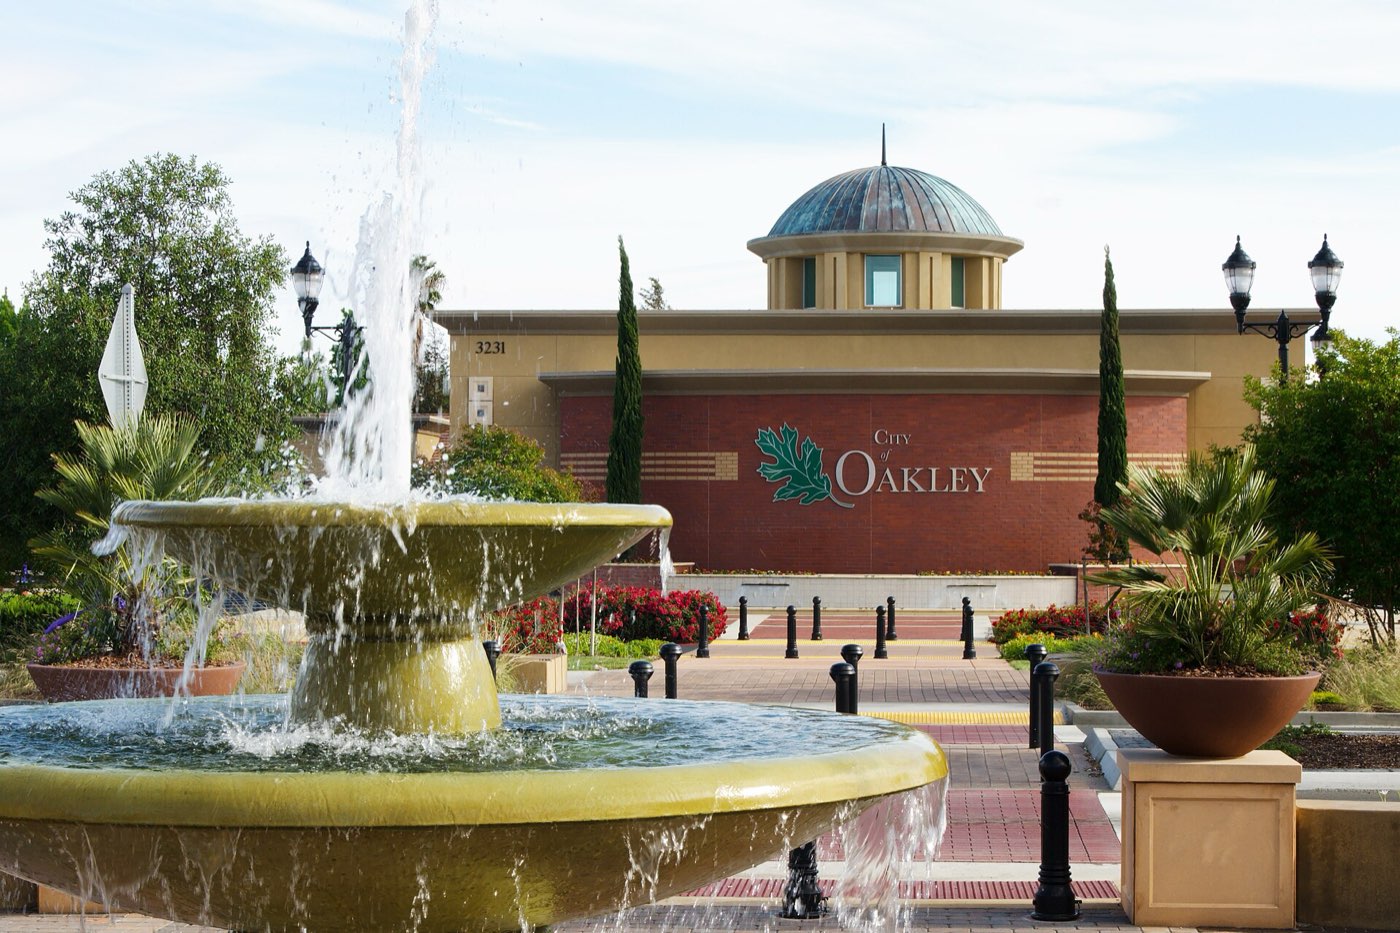
Oakley is a growing Delta town east of Antioch along Highway 4 and Main Street, known for the Big Break Regional Shoreline, its vineyards and new subdivisions, and quick access to Bethel Island and the Delta waterways. We help Oakley buyers and homeowners with FHA, VA, USDA and conventional purchase loans, down payment assistance and refinances. Buyers of higher-priced homes in Oakley are often surprised at how much the terms of a jumbo loan can move with small changes in the file. A slightly higher credit score, a few more months of reserves or a different ownership structure for a business can shift pricing meaningfully. PNL spends the first conversation understanding how you earn and hold your money, then runs the scenario through several jumbo lenders before anyone pulls credit. That preparation is what lets an Oakley jumbo loan close on time with terms you understood from the start.
Call Pacific National Lending for jumbo loans in Oakley: (916) 526-2700
Get Pre-approved
Housing is mostly 1990s and 2000s subdivisions such as Summer Lake, Cypress Grove, Laurel Woods and Vintage Parkway, newer homes in Emerson Ranch and Delaney Park, and older homes and small ranch properties around downtown Main Street. Jumbo pricing in Oakley depends on loan amount, credit score, down payment, reserves and property type. We show you how a slightly larger down payment or a different loan structure changes the rate, and we can sometimes split financing into a conforming first and a second loan to save money.
Get Pre-approved
Oakley is one of the few places in Contra Costa County where a first-time buyer can still find a newer detached home within FHA and conventional limits, so FHA, VA and down payment assistance borrowers and families moving out from the inner Bay Area make up most of the market. We check whether a specific address qualifies for USDA zero-down financing, run the file as FHA and conventional alongside it, and compare builder incentives against outside lenders for buyers in the new subdivisions. Our jumbo process in Oakley starts with a detailed review of income and assets, because jumbo underwriting asks more questions. A fully underwritten pre-approval from PNL gives listing agents confidence that a large loan will actually close, which matters in competitive offers.
Many jumbo lenders offer relationship pricing when assets are moved to the institution, and some allow gift funds or lower reserves for strong borrowers. We lay out these options for every Oakley jumbo file so you can decide what is worth it.
From Downtown Oakley, Summer Lake, Cypress Grove, Emerson Ranch to the edges of Oakley, we have closed loans on the kinds of homes and lots that are typical of far east Contra Costa County. Oakley is about seventy minutes from Gold River via Highway 160 through the Delta, and clients there work with us by phone, email and e-signature or stop by the office when they are in the Sacramento area.
The quickest way to find out what jumbo loans would look like for your Oakley situation is a ten-minute call to (916) 526-2700. Prefer to type? The short form on this page reaches the same loan officers.
Get Pre-approvedLearn more about the program itself: Jumbo Loans · All loan options · Purchase · Refinance · Today's rates
Yes. Several jumbo lenders accept one year of tax returns or twelve to twenty-four months of bank statements, and some count a portion of liquid assets toward qualifying. Jason is self-employed himself and reads profit and loss statements for a living, so a complicated Oakley jumbo file is familiar territory.
Not always. Jumbo rates move with their own market and at times have been lower than conforming rates for well-qualified borrowers, while at other times they run higher. The spread depends on the lender, your credit, the down payment and the property. Because the gap changes week to week, we price both options when an Oakley loan amount is close to the conforming limit and recommend whichever produces the better outcome.
Yes. Jumbo rate-and-term and cash-out refinances are available, and homeowners in Oakley who bought when rates were higher or whose equity has grown often have good reason to look. Cash-out limits are usually tighter than on purchases, and the appraisal carries more weight at higher values. We compare your current loan against several lenders and give you a break-even figure so you can decide whether a refinance is worth the cost.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.