
Clayton attracts move-up families leaving Concord and Walnut Creek for larger lots, quiet streets and Mount Diablo Elementary, and most detached purchases here are jumbo loans or sit right at the conventional limit, so we price both structures for the buyer. Longtime owners with substantial equity often come to us for HELOCs, cash-out refinances or a reverse mortgage comparison once they retire in place. Buyers of higher-priced homes in Clayton are often surprised at how much the terms of a jumbo loan can move with small changes in the file. A slightly higher credit score, a few more months of reserves or a different ownership structure for a business can shift pricing meaningfully. PNL spends the first conversation understanding how you earn and hold your money, then runs the scenario through several jumbo lenders before anyone pulls credit. That preparation is what lets an Clayton jumbo loan close on time with terms you understood from the start.
Call Pacific National Lending for jumbo loans in Clayton: (916) 526-2700
Get Pre-approved
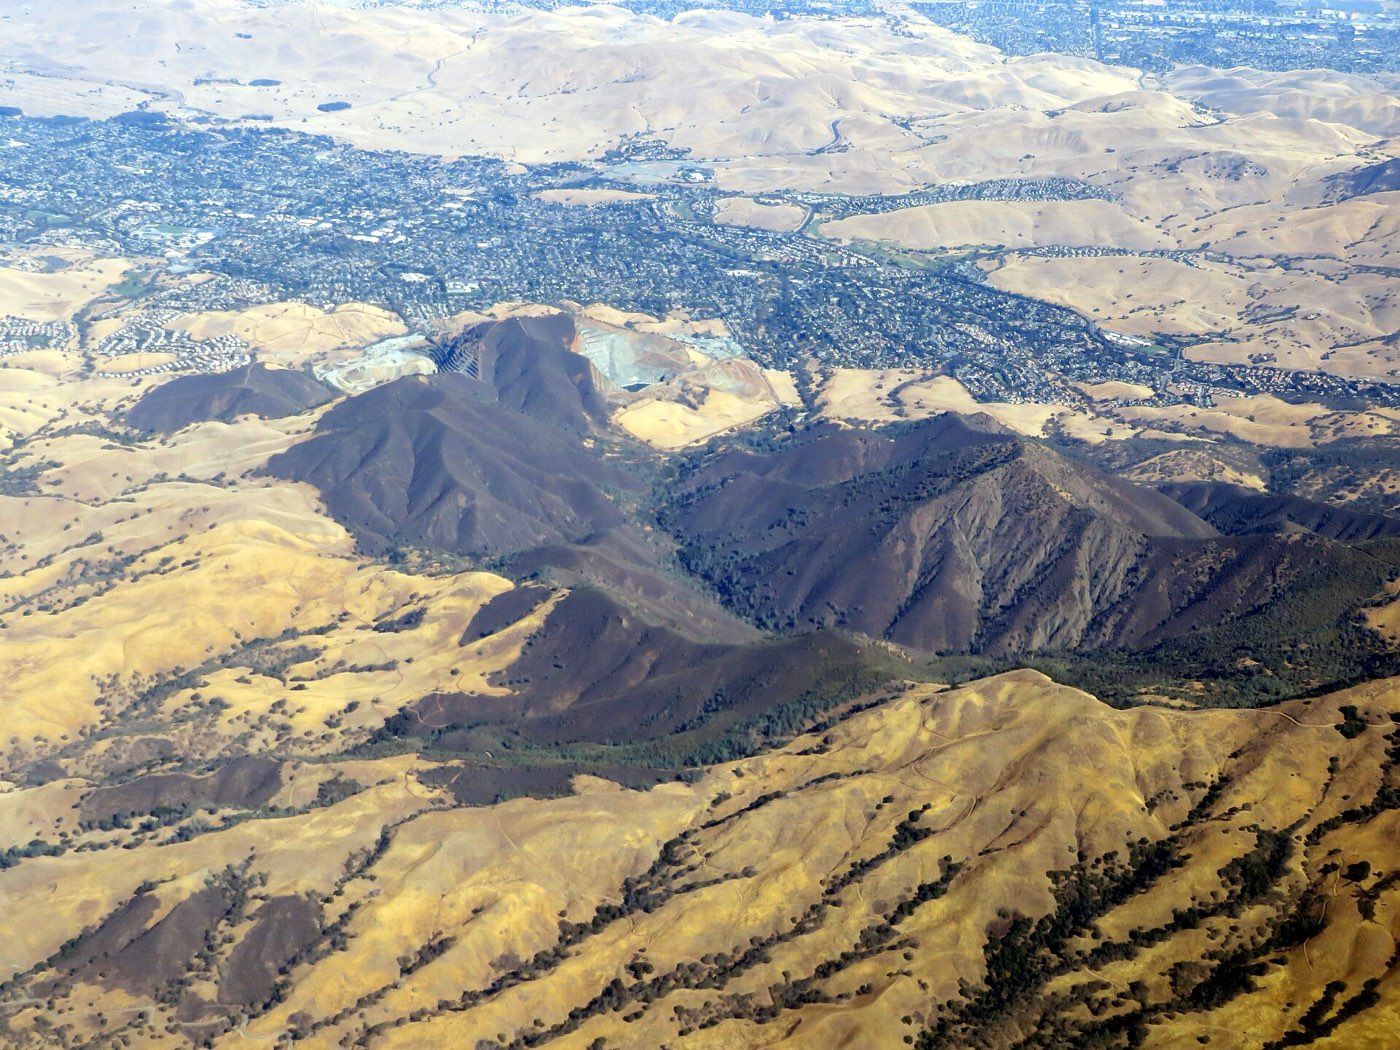
Tucked against the northern base of Mount Diablo at the end of Clayton Road, Clayton is a small town with a historic Main Street downtown, the Oakhurst golf course community and direct access to Mount Diablo State Park and the Marsh Creek Road backcountry. We help Clayton buyers and homeowners with jumbo and conventional purchase loans, refinances and home equity lines. Lenders price jumbo loans in Clayton on risk, and the inputs are concrete: loan-to-value, credit score, property type, occupancy and whether the loan is a purchase or cash-out refinance. Second homes and condominiums carry adjustments at many lenders, while a primary residence with 25 percent or more down usually sees the best terms. Rather than guessing, we price your exact scenario across our lender list and show how each variable changes the result, so an Clayton buyer can decide whether putting more down or restructuring the loan is worth it.
Get Pre-approved
Housing is mostly 1970s and 80s single-family homes in Dana Hills and Regency Woods, 1990s homes in the Oakhurst, Peacock Creek and Eagle Peak subdivisions, and a handful of older homes and ranchettes around the downtown and along Marsh Creek Road. Business owners, physicians in private practice and commission-based professionals make up a large share of the jumbo borrowers we work with in Clayton, and their income rarely fits a W-2 template. Some lenders average two years of returns, some use the most recent year when income is rising, and others accept bank statements or a profit and loss prepared by a CPA. Depreciation, one-time write-offs and retained earnings all get treated differently from lender to lender. Knowing which guideline helps your file is the heart of brokering a jumbo loan in Clayton.
Jumbo files in Clayton are where thorough documentation pays off. Jumbo lenders want to see income, assets and reserves clearly, and self-employed borrowers can often use bank statements or a single year of returns with the right lender. Because we compare several jumbo investors, a strong file gets priced competitively instead of taking whatever one bank offers.
Whether you are in Downtown Clayton, Oakhurst, Dana Hills, Regency Woods or elsewhere in Clayton, the process for jumbo loans is the same: one loan officer, clear numbers and a lender chosen to fit your file. Clayton is about ninety minutes from our Gold River office, and we handle files there by phone, email and secure e-signature just as we do for the rest of the East Bay.
The quickest way to find out what jumbo loans would look like for your Clayton situation is a ten-minute call to (916) 526-2700. Prefer to type? The short form on this page reaches the same loan officers.
Get Pre-approvedLearn more about the program itself: Jumbo Loans · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of northwest foothills of Mount Diablo, October 2020" by Pi.1415926535, CC BY-SA 4.0.
Yes, and self-employed borrowers are a large part of the jumbo market in Clayton. Traditional programs use two years of personal and business tax returns, while alternative programs qualify on a year or two of business or personal bank deposits, CPA-prepared statements or liquid assets. Each approach has different pricing and requirements, and the best fit depends on how your business reports income. We review your returns first and then recommend the path that supports the loan you need.
Reserves are the months of mortgage payments you must still have in verified accounts after the down payment and closing costs are paid. Requirements vary widely by lender and loan size, commonly ranging from six to twelve months and sometimes more on very large loans or second homes. Retirement accounts often count at a discounted value. We confirm the exact reserve requirement for your Clayton scenario before you commit to a purchase.
Yes. Jumbo rate-and-term and cash-out refinances are available, and homeowners in Clayton who bought when rates were higher or whose equity has grown often have good reason to look. Cash-out limits are usually tighter than on purchases, and the appraisal carries more weight at higher values. We compare your current loan against several lenders and give you a break-even figure so you can decide whether a refinance is worth the cost.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.