
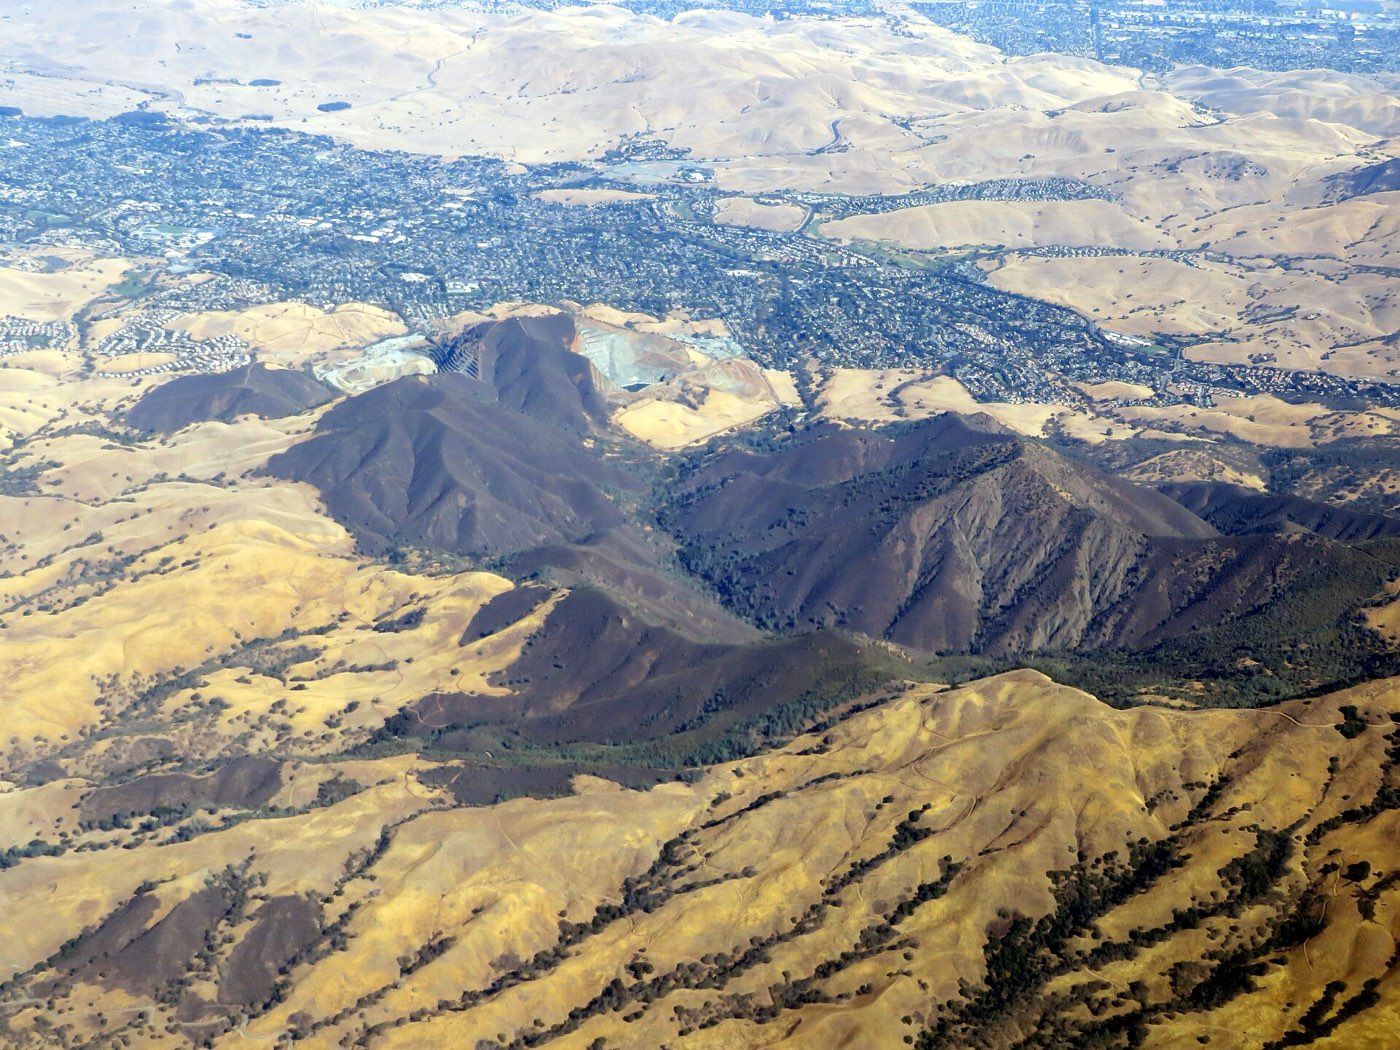
Tucked against the northern base of Mount Diablo at the end of Clayton Road, Clayton is a small town with a historic Main Street downtown, the Oakhurst golf course community and direct access to Mount Diablo State Park and the Marsh Creek Road backcountry. We help Clayton buyers and homeowners with jumbo and conventional purchase loans, refinances and home equity lines. Saving 20 percent for a home in Clayton can take years, and most buyers do not need to. Pacific National Lending helps Clayton buyers use low down payment programs, gift funds, seller credits and assistance programs to close with a fraction of what they expected.
Call Pacific National Lending for low down payment mortgages in Clayton: (916) 526-2700
Get Pre-approved
Clayton attracts move-up families leaving Concord and Walnut Creek for larger lots, quiet streets and Mount Diablo Elementary, and most detached purchases here are jumbo loans or sit right at the conventional limit, so we price both structures for the buyer. Longtime owners with substantial equity often come to us for HELOCs, cash-out refinances or a reverse mortgage comparison once they retire in place. Your down payment in Clayton can come from savings, a gift from a relative, a 401(k) loan, the sale of assets or a down payment assistance program. We document each source correctly so underwriting goes smoothly, and we show you how the choice affects your rate and mortgage insurance.
Get Pre-approved
Housing is mostly 1970s and 80s single-family homes in Dana Hills and Regency Woods, 1990s homes in the Oakhurst, Peacock Creek and Eagle Peak subdivisions, and a handful of older homes and ranchettes around the downtown and along Marsh Creek Road. Qualifying for a low down payment loan in Clayton follows the same underwriting path as any mortgage: verified income, credit review, asset statements and an appraisal. What changes is the attention paid to where the down payment comes from. Lenders want a paper trail for gifted money, for funds pulled from a retirement account and for any large deposit that does not match your pay. Pacific National Lending walks Clayton buyers through that documentation before the application goes in, which avoids last-minute conditions and keeps the closing date intact.
Condos and townhomes are a common first purchase in Clayton, and low down payment programs treat them a little differently. Conventional lenders review the homeowners association budget and owner-occupancy, and FHA requires the project or the unit to meet its own approval rules. Pacific National Lending checks the property early so a Clayton buyer does not fall in love with a unit that the chosen program will not finance.
Clayton borrowers in Downtown Clayton, Oakhurst, Dana Hills, Regency Woods and the surrounding neighborhoods work with us for low down payment mortgages because the advice is local and the pricing is shopped. Clayton is about ninety minutes from our Gold River office, and we handle files there by phone, email and secure e-signature just as we do for the rest of the East Bay.
For low down payment mortgages in Clayton, call Pacific National Lending at (916) 526-2700 or use the secure application on this page. A licensed loan officer will follow up within one business day.
Get Pre-approvedLearn more about the program itself: Low Down Payment Mortgage · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of northwest foothills of Mount Diablo, October 2020" by Pi.1415926535, CC BY-SA 4.0.
Less than most people assume. A conventional loan can be done with 3 percent down for qualifying buyers, FHA requires 3.5 percent, and VA and USDA allow zero down for eligible borrowers. You will also need money for closing costs and prepaid items, though seller credits, lender credits and gift funds can cover part of that. Pacific National Lending builds a full cash-to-close estimate for every Clayton buyer before you write an offer.
Yes, on most programs. Conventional, FHA and VA loans allow gift funds from family members and certain other donors for the down payment and closing costs, though each program has its own rules about who can give and how the transfer is documented. The donor signs a gift letter and the lender traces the funds. We tell Clayton buyers exactly what paperwork to gather so the gift does not slow down underwriting.
Usually yes, for two reasons: the loan balance is larger, and mortgage insurance is added until it can be removed. How much more depends on the program, your credit score and the lender. Conventional PMI can drop off as equity builds, while FHA insurance often remains for the life of the loan unless you refinance. Pacific National Lending shows Clayton buyers the payment for each program so the difference is clear before you decide.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.