
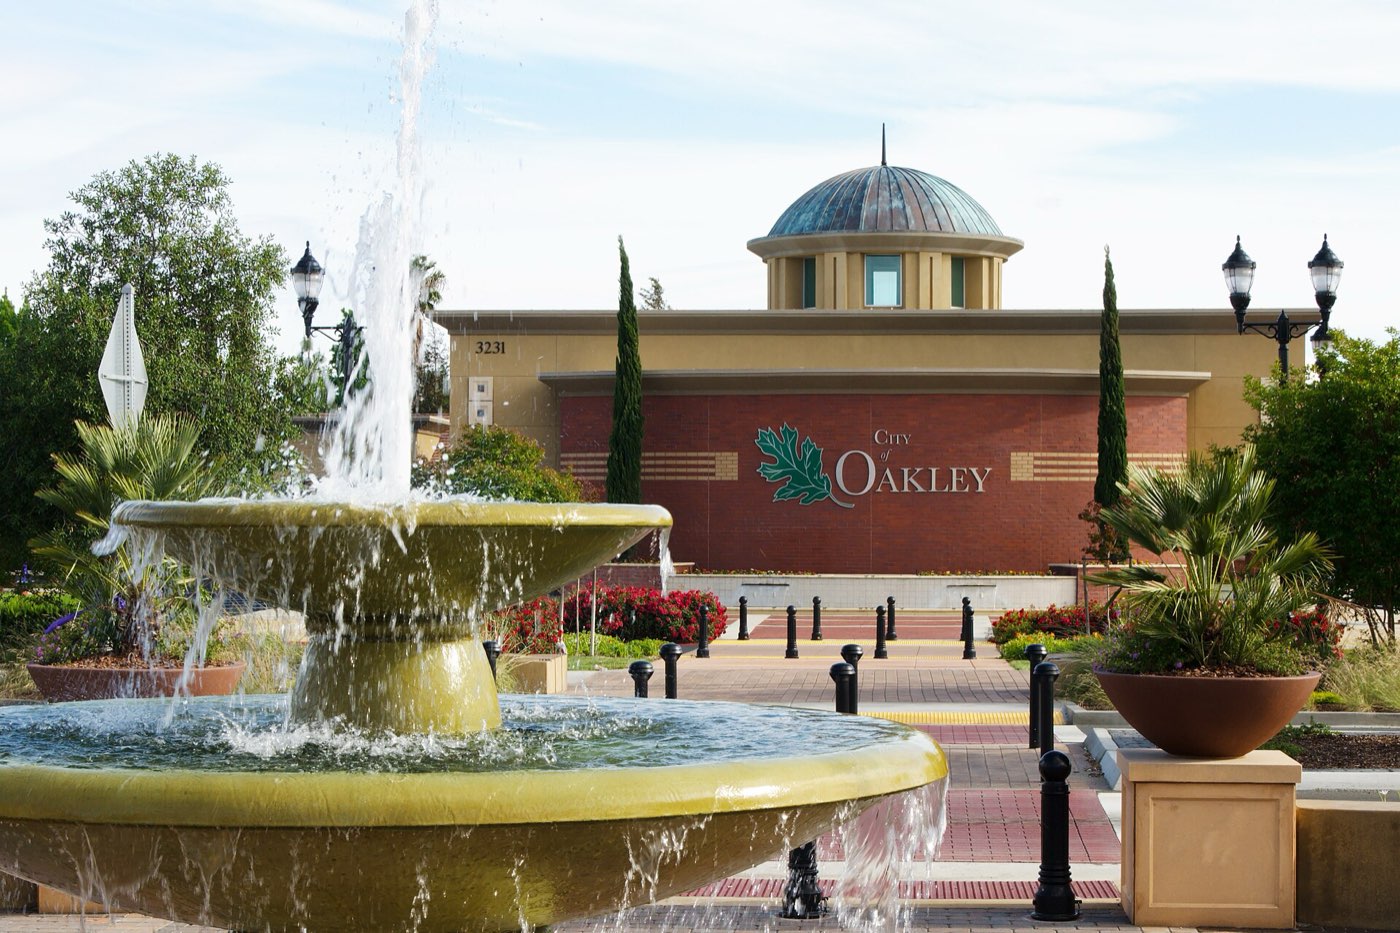
Oakley is a growing Delta town east of Antioch along Highway 4 and Main Street, known for the Big Break Regional Shoreline, its vineyards and new subdivisions, and quick access to Bethel Island and the Delta waterways. We help Oakley buyers and homeowners with FHA, VA, USDA and conventional purchase loans, down payment assistance and refinances. The idea that you need 20 percent down to buy a home in Oakley keeps a lot of qualified households renting longer than they should. In practice, most purchase loans we broker close with much less. Conventional financing allows 3 percent down for qualifying buyers, FHA requires 3.5 percent, and VA and USDA permit zero down for borrowers who meet their eligibility rules. Pacific National Lending lines these programs up for Oakley buyers, explains how each one treats mortgage insurance, and recommends the structure that leaves you with the lowest total cost rather than just the smallest check at closing.
Call Pacific National Lending for low down payment mortgages in Oakley: (916) 526-2700
Get Pre-approved
Oakley is one of the few places in Contra Costa County where a first-time buyer can still find a newer detached home within FHA and conventional limits, so FHA, VA and down payment assistance borrowers and families moving out from the inner Bay Area make up most of the market. We check whether a specific address qualifies for USDA zero-down financing, run the file as FHA and conventional alongside it, and compare builder incentives against outside lenders for buyers in the new subdivisions. Mortgage insurance is the trade-off that comes with putting less down, and it works differently from one program to the next. On a conventional loan in Oakley, private mortgage insurance is priced on your credit score and down payment, and it can be removed later once the loan balance falls to a certain share of the home's value. FHA charges an upfront premium plus an annual premium, and for most borrowers who start with the minimum down payment that annual premium stays for the life of the loan. VA charges a one-time funding fee instead of monthly insurance. We run the numbers on each for Oakley buyers.
Get Pre-approved
Housing is mostly 1990s and 2000s subdivisions such as Summer Lake, Cypress Grove, Laurel Woods and Vintage Parkway, newer homes in Emerson Ranch and Delaney Park, and older homes and small ranch properties around downtown Main Street. Our low down payment loan process in Oakley starts with a fully underwritten pre-approval that considers every program you qualify for. From there it is the same clear path as any purchase: documents, appraisal, final approval and closing in about three weeks.
First-time buyers in Oakley can often layer CalHFA's MyHome assistance or local programs on top of a low down payment loan, reducing cash to close even further. We check eligibility for every buyer who might qualify.
Our low down payment mortgages clients in Oakley come from Downtown Oakley, Summer Lake, Cypress Grove, Emerson Ranch and every other part of far east Contra Costa County. Oakley is about seventy minutes from Gold River via Highway 160 through the Delta, and clients there work with us by phone, email and e-signature or stop by the office when they are in the Sacramento area.
For low down payment mortgages in Oakley, call Pacific National Lending at (916) 526-2700 or use the secure application on this page. A licensed loan officer will follow up within one business day.
Get Pre-approvedLearn more about the program itself: Low Down Payment Mortgage · All loan options · Purchase · Refinance · Today's rates
Yes, on most programs. Conventional, FHA and VA loans allow gift funds from family members and certain other donors for the down payment and closing costs, though each program has its own rules about who can give and how the transfer is documented. The donor signs a gift letter and the lender traces the funds. We tell Oakley buyers exactly what paperwork to gather so the gift does not slow down underwriting.
Less than most people assume. A conventional loan can be done with 3 percent down for qualifying buyers, FHA requires 3.5 percent, and VA and USDA allow zero down for eligible borrowers. You will also need money for closing costs and prepaid items, though seller credits, lender credits and gift funds can cover part of that. Pacific National Lending builds a full cash-to-close estimate for every Oakley buyer before you write an offer.
It depends on the program and the lender. FHA accepts lower scores than conventional financing, and VA lenders set their own minimums. Conventional 3 percent down programs tend to favor stronger credit and reward it with cheaper mortgage insurance. Rather than quote one number, Pacific National Lending reviews your credit profile and tells you which low down payment options are open to you as a Oakley buyer and what each would cost.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.