
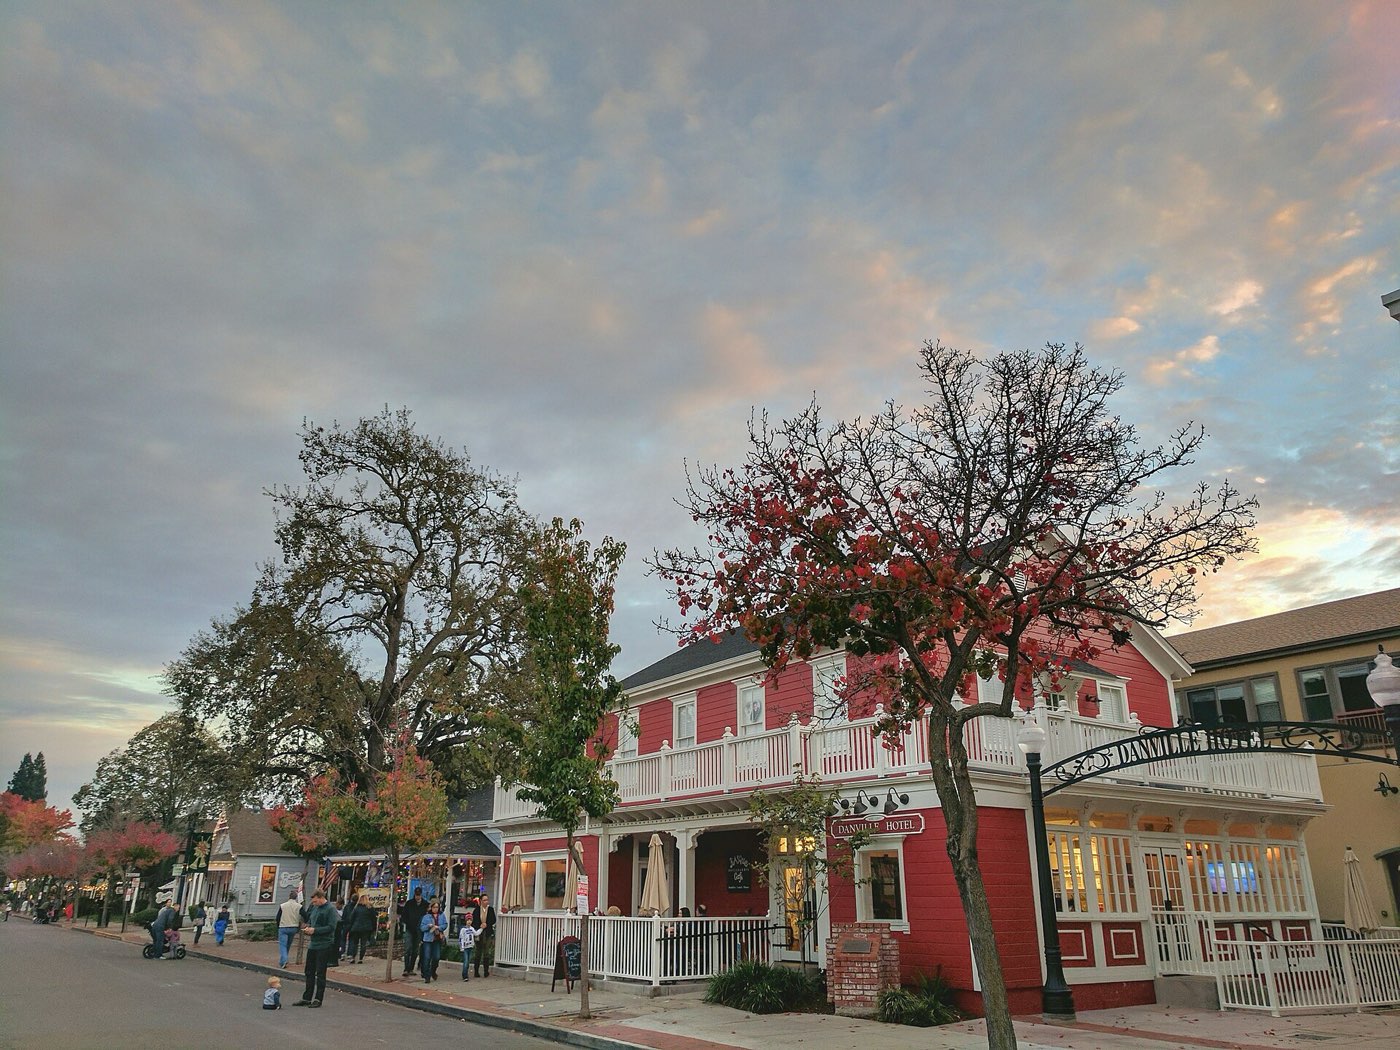
Danville is the heart of the San Ramon Valley along I-680, known for its walkable Hartz Avenue downtown, the Iron Horse Regional Trail, the gated Blackhawk community and the San Ramon Valley Unified schools, with Mount Diablo rising to the east. We help Danville buyers and homeowners with jumbo purchase loans, jumbo refinances, equity lines and reverse mortgages. Before touring a single home in Danville, it pays to know what a lender will actually approve. A pre-approval from Pacific National Lending answers that question with documentation rather than a guess: a loan officer reads the pay stubs, the tax returns, the bank statements and the credit report, and the resulting letter states a loan amount and program a lender has signed off on. Danville agents recognize the difference between that and a form letter generated after a five-minute phone call.
Call Pacific National Lending for home loan pre-approval in Danville: (916) 526-2700
Get Pre-approved
Housing includes 1950s and 60s ranch homes on the Westside and in Sycamore and Greenbrook, 1980s and 90s custom and semi-custom homes in Blackhawk and Magee Ranch, and 2000s homes in the Alamo Creek area toward the Tassajara Valley. Listing agents in Danville read pre-approval letters carefully because a weak one costs their seller time. They look for a lender who is reachable, a loan officer's direct contact information, a statement that documents and credit were actually reviewed, and a loan structure that matches the offer. Many agents call the lender before advising the seller which offer to accept. When they call PNL about a Danville buyer, they reach the person who reviewed the file, not a call center.
Get Pre-approved
Nearly every Danville purchase is a jumbo loan, and buyers are typically executives, Tri-Valley and San Francisco professionals and relocating families who care about the schools and are often selling another home at the same time. We work through reserves, bridge options and asset-based qualifying for these files, and we compare jumbo pricing across our lender panel because the spread between lenders on a large loan is real money. Pre-approvals have a shelf life because the information behind them changes. Credit reports expire, pay stubs and bank statements age out, and rates move. While you are shopping in Danville, we refresh the file as needed so the letter stays valid, and we re-run the numbers if rates shift enough to affect your budget. When you find the house, we issue a letter at the exact offer price, which avoids showing a seller more buying power than you need to.
A pre-approval letter is not a commitment to lend, and we say so plainly. It is a lender's informed opinion that the Danville buyer qualifies, subject to an acceptable property, an appraisal that supports the price and no material change in the borrower's situation. Treating it as the serious review it is makes those conditions easy to meet.
We help borrowers with home loan pre-approval throughout Danville, including Downtown Danville, Blackhawk, Westside Danville, Sycamore, and across the San Ramon Valley. Danville is roughly ninety minutes to two hours from Gold River by I-80 and I-680, and our San Ramon Valley clients complete the process with us by phone, email and e-signature.
Questions about home loan pre-approval in Danville are what we do all day. Reach Pacific National Lending at (916) 526-2700, or start online and we will call you back with specifics rather than a sales pitch.
Get Pre-approvedLearn more about the program itself: Home Loan Pre-Approval · All loan options · Purchase · Refinance · Today's rates
Area photo: "Hartz Avenue Danville California" by Danvilleca, CC BY-SA 4.0.
A mortgage credit inquiry typically has a small, temporary effect on your score, often a few points. Credit scoring models also treat multiple mortgage inquiries within a short shopping window as a single inquiry, so comparing lenders does not compound the effect. We do not pull credit at the first conversation, only once a Danville buyer decides to move forward.
Often yes. If you have a written offer letter and your first paycheck will arrive before your first mortgage payment is due, most programs let us use that income. Self-employed Danville buyers may qualify with one year of tax returns instead of two. Income documentation is the heart of the file, so send us what you have and we will tell you what counts.
For most Danville buyers: a month of pay stubs, two years of W-2s or tax returns, two months of bank statements for every account holding down payment funds, a photo ID and details on any other real estate you own. Self-employed borrowers add business returns and a year-to-date profit and loss statement. We send a checklist tailored to your situation.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.