
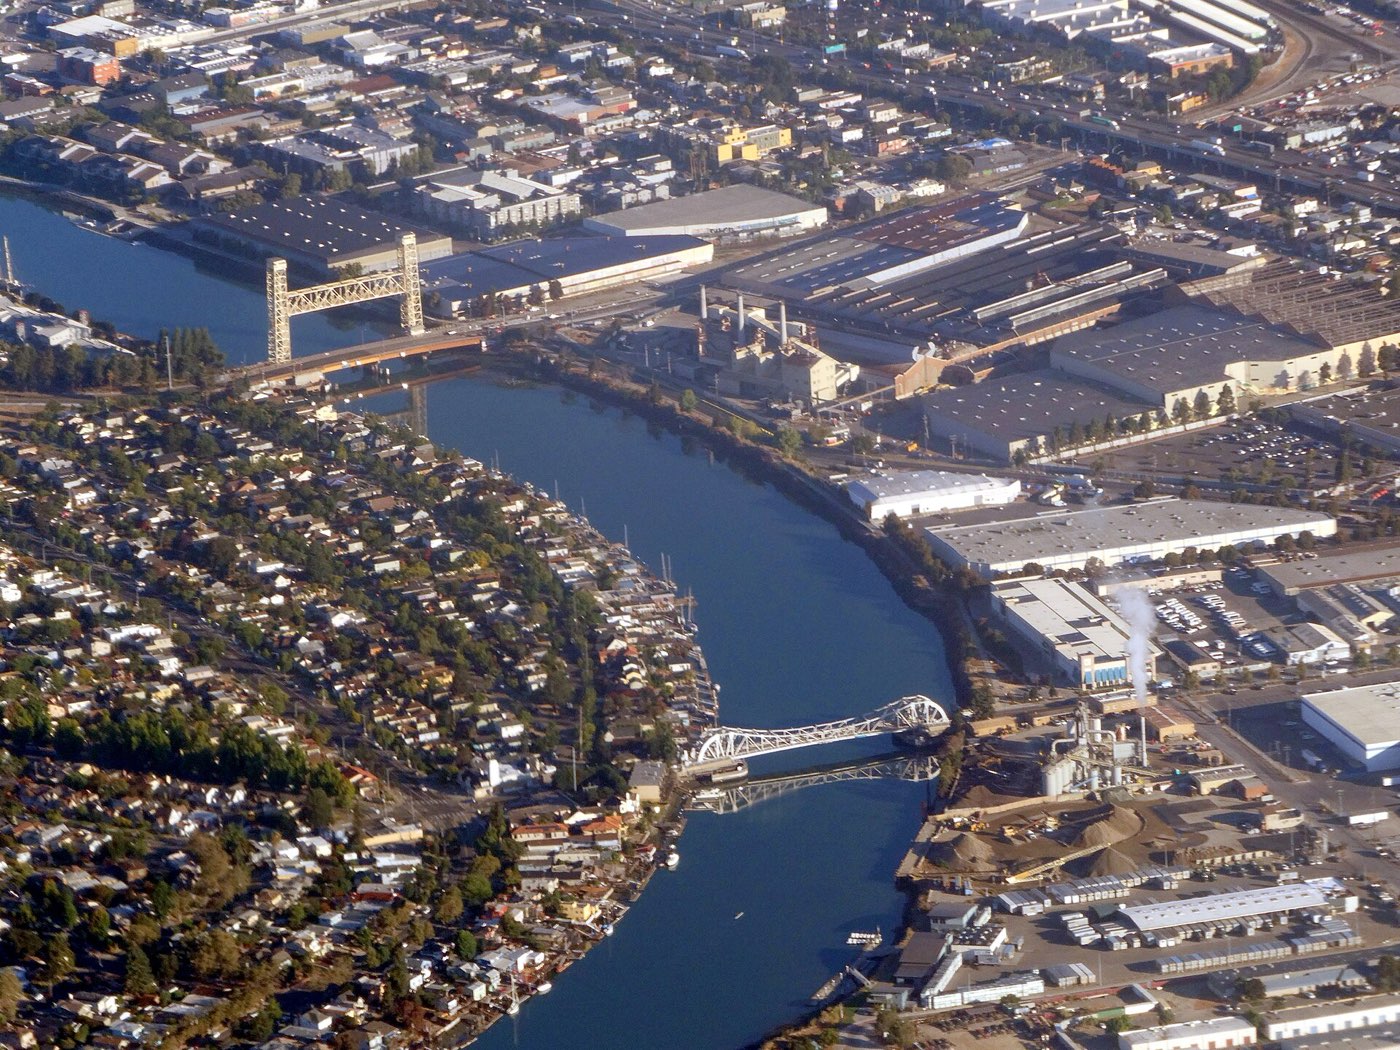
Alameda is an island city across the Oakland Estuary, reached by the Posey and Webster tubes, the Park Street and Fruitvale bridges and a ferry to San Francisco, and it is known for its Victorian homes, the Park Street and Webster Street shopping districts and the redeveloping former Naval Air Station at Alameda Point. We help Alameda buyers and homeowners with jumbo purchase loans, refinances, equity lines and reverse mortgages. Home values in Alameda have built substantial equity for many owners, and a HELOC turns that equity into a flexible resource for remodels, tuition, debt consolidation or an investment down payment. Pacific National Lending explains how HELOCs work and when they beat a cash-out refinance.
Call Pacific National Lending for a home equity line of credit in Alameda: (916) 526-2700
Get Pre-approved
Housing ranges from Victorian and Craftsman homes in the Gold Coast, Fernside and the East End to 1960s and 70s homes on Bay Farm Island and Harbor Bay, with condos and townhomes along South Shore, the West End and the new Alameda Point and Marina Village developments. Every HELOC in Alameda has two phases. During the draw period you can borrow, repay and borrow again, usually with interest-only minimum payments. When the draw period ends, the line converts to a repayment period during which no new advances are allowed and the balance is paid down with principal and interest. The length of each phase depends on the lender. The rate is variable and moves with a published index, so Alameda homeowners should plan for payments that can rise as well as fall.
Get Pre-approved
Most Alameda purchases land in jumbo territory, and the buyers are usually two-income households who want a quieter, flatter alternative to Oakland or San Francisco with a ferry or tube commute. Older homes here often need a lender who is comfortable with foundation, pest and dry-rot findings, so we structure the pre-approval around the actual property, and we compare conventional, jumbo and VA options for every file rather than defaulting to one program. Opening a HELOC in Alameda involves an application, a credit report, income documentation and a valuation of the home. For smaller lines some lenders accept a desktop valuation or an exterior inspection instead of a full appraisal, which saves time and money. Once approved you sign the line agreement, wait out the short cancellation window that federal law requires on a primary residence, and then the funds are available. Many Alameda homeowners have their line open within a few weeks of applying.
To see how much equity you could access with a HELOC on your Alameda home, call (916) 526-2700 or apply online. We will compare lenders and give you a clear answer with no obligation.
We help borrowers with a home equity line of credit throughout Alameda, including Gold Coast, Fernside, East End, West End, and across the East Bay. Alameda is roughly two hours west of our Gold River office, so our clients there handle the whole loan by phone, email and secure e-signature without ever needing to make the drive.
Ready to talk about a home equity line of credit in Alameda? Call (916) 526-2700 or apply online in a few minutes. There is no credit pull at the first step and no obligation.
Get Pre-approvedLearn more about the program itself: HELOC · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of Oakland Estuary bridges, September 2024" by Pi.1415926535, CC BY-SA 4.0.
The line closes to new borrowing and enters repayment. Your payment switches from interest-only to principal and interest on whatever balance remains, so it typically goes up. The repayment term depends on the lender. Homeowners in Alameda who want to avoid that jump can pay the balance down early, refinance the line or open a new one, subject to qualifying.
The limit is based on your home's current value, what you still owe on the first mortgage and the lender's maximum combined loan-to-value. Subtract the mortgage balance from the allowed percentage of value and the remainder is roughly your available line, subject to credit and income review. Each lender sets its own cap, so Pacific National Lending compares several for Alameda homeowners.
If the current market rate is better than the rate on your first mortgage, a cash-out refinance can lower your rate and pull money out at the same time. If your first-mortgage rate is better than today's, leave it alone and use a HELOC so you only pay interest on what you use. We run both options for Alameda homeowners, short-term cost and long-term cost side by side.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.