
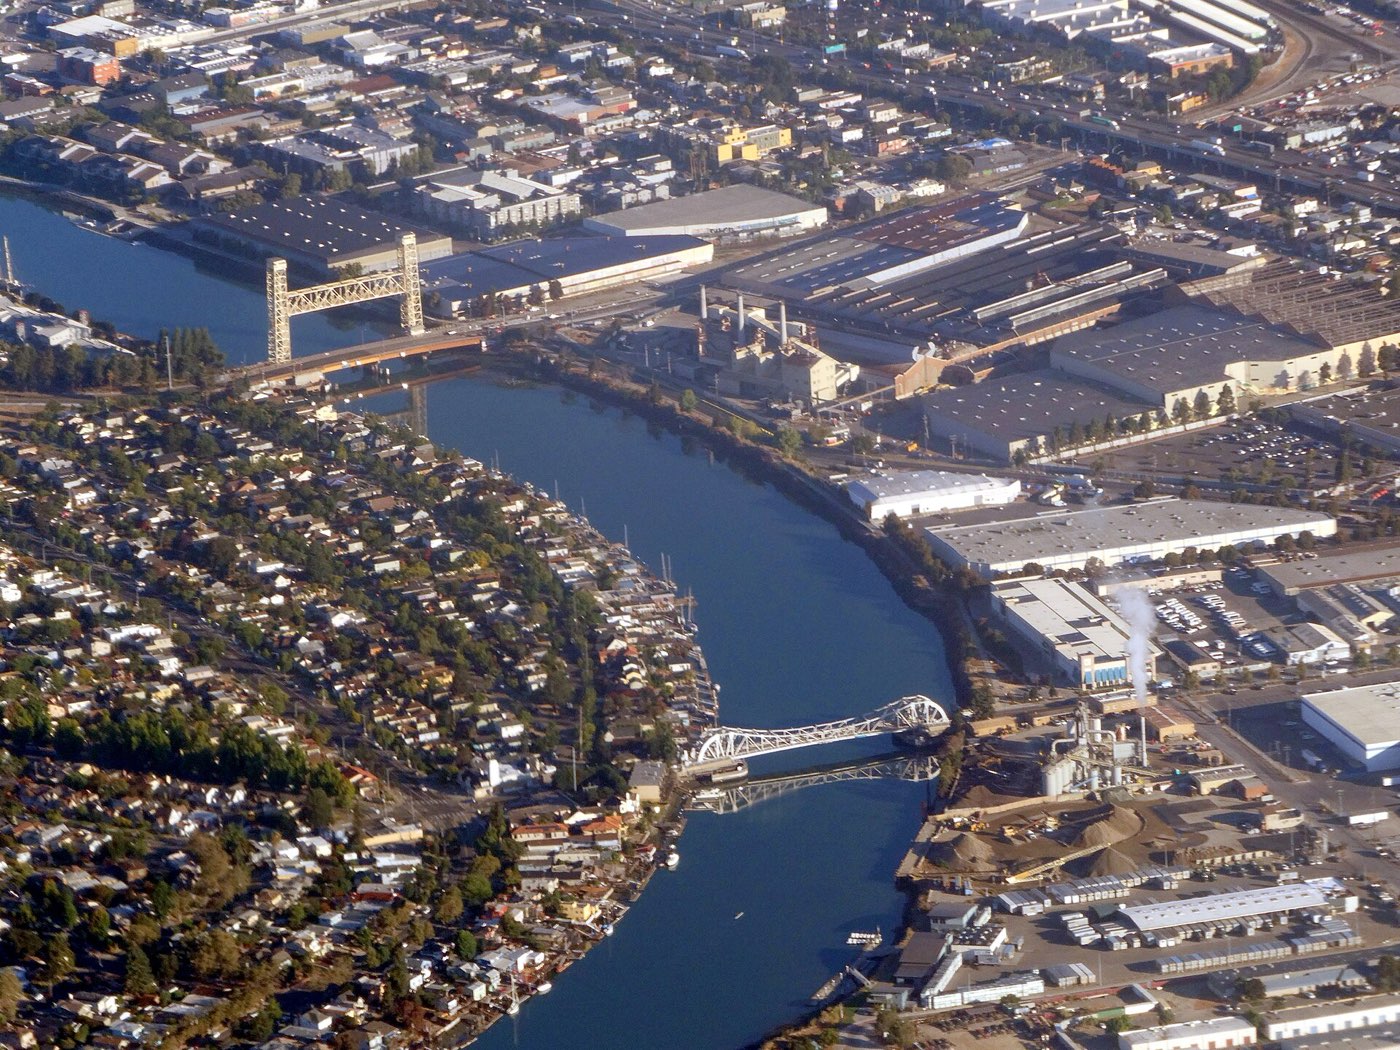
Alameda is an island city across the Oakland Estuary, reached by the Posey and Webster tubes, the Park Street and Fruitvale bridges and a ferry to San Francisco, and it is known for its Victorian homes, the Park Street and Webster Street shopping districts and the redeveloping former Naval Air Station at Alameda Point. We help Alameda buyers and homeowners with jumbo purchase loans, refinances, equity lines and reverse mortgages. Shopping for a home loan in Alameda means more than finding the lowest advertised rate. Points, lender fees, mortgage insurance and the loan program itself all change what you actually pay, and PNL lays those numbers out side by side so you can make a confident choice.
Call Pacific National Lending for home loans in Alameda: (916) 526-2700
Get Pre-approved
Housing ranges from Victorian and Craftsman homes in the Gold Coast, Fernside and the East End to 1960s and 70s homes on Bay Farm Island and Harbor Bay, with condos and townhomes along South Shore, the West End and the new Alameda Point and Marina Village developments. The loan program that fits an Alameda purchase often depends on the property as much as the borrower. Condos need lender-approved projects, older homes must meet FHA and VA condition standards, and rural parcels may qualify for USDA financing. We check these details before you write an offer, not after.
Get Pre-approved
Most Alameda purchases land in jumbo territory, and the buyers are usually two-income households who want a quieter, flatter alternative to Oakland or San Francisco with a ferry or tube commute. Older homes here often need a lender who is comfortable with foundation, pest and dry-rot findings, so we structure the pre-approval around the actual property, and we compare conventional, jumbo and VA options for every file rather than defaulting to one program. Once a Alameda seller accepts your offer, the home loan moves through a predictable sequence: the rate lock, the appraisal order, submission to underwriting, a conditional approval with a short list of items to clear, then final approval and loan documents sent to escrow. Most of the work happens behind the scenes. Your part is to respond quickly to document requests and to avoid opening new credit or moving large sums between accounts until the loan funds and the keys are yours.
First-time buyers in Alameda may also qualify for down payment assistance through CalHFA and local programs, which can be layered with FHA or conventional financing to reduce cash to close. We check eligibility for every first-time buyer we work with.
Whether you are in Gold Coast, Fernside, East End, West End or elsewhere in Alameda, the process for home loans is the same: one loan officer, clear numbers and a lender chosen to fit your file. Alameda is roughly two hours west of our Gold River office, so our clients there handle the whole loan by phone, email and secure e-signature without ever needing to make the drive.
The quickest way to find out what home loans would look like for your Alameda situation is a ten-minute call to (916) 526-2700. Prefer to type? The short form on this page reaches the same loan officers.
Get Pre-approvedLearn more about the program itself: Home Loans · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of Oakland Estuary bridges, September 2024" by Pi.1415926535, CC BY-SA 4.0.
Closing costs include lender fees, appraisal, title insurance, escrow charges, recording fees and prepaid items such as property taxes and homeowners insurance. The buyer typically pays them, but sellers in Alameda can contribute within program limits, and lender credits can offset some costs in exchange for a slightly higher rate. Your loan estimate lists every item before you commit.
A fixed rate makes sense when you plan to keep the home and the loan for many years and want a payment that never changes. An adjustable loan with a five- or seven-year fixed period can carry a lower starting rate and suits buyers who expect to sell or refinance before it adjusts. We show Alameda buyers both payments and the worst-case adjustment so the choice is informed.
Do not make large purchases or open new credit until the loan funds. New furniture on store financing is the classic mistake, and a job change is the other. We pre-approve carefully so that, barring a lost job, every Alameda file we approve closes, but a new payment that shows up mid-process can undo that.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.