
Most Alameda purchases land in jumbo territory, and the buyers are usually two-income households who want a quieter, flatter alternative to Oakland or San Francisco with a ferry or tube commute. Older homes here often need a lender who is comfortable with foundation, pest and dry-rot findings, so we structure the pre-approval around the actual property, and we compare conventional, jumbo and VA options for every file rather than defaulting to one program. The pre-approval is also where most of the problem-solving on a Alameda purchase gets done. If a credit report shows an old collection, if a bonus needs to be documented a certain way, or if the down payment is coming from several sources, these are far easier to address before you are in contract than during a tight escrow. PNL treats the pre-approval as the real underwriting step for Alameda buyers, and the closing becomes mostly paperwork as a result.
Call Pacific National Lending for home loan pre-approval in Alameda: (916) 526-2700
Get Pre-approved
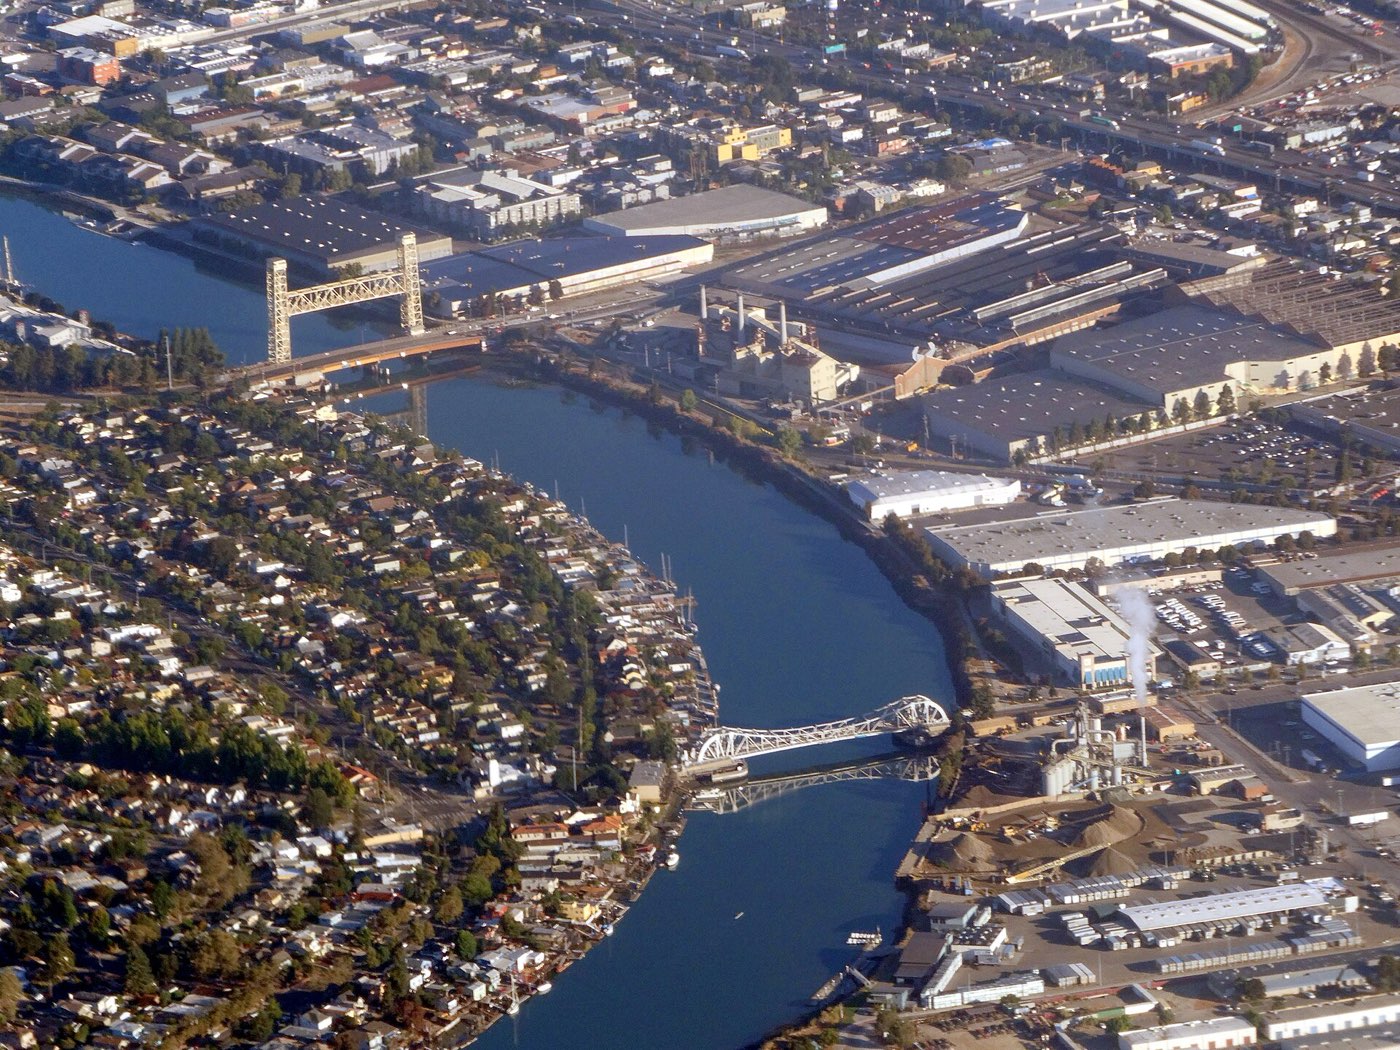
Alameda is an island city across the Oakland Estuary, reached by the Posey and Webster tubes, the Park Street and Fruitvale bridges and a ferry to San Francisco, and it is known for its Victorian homes, the Park Street and Webster Street shopping districts and the redeveloping former Naval Air Station at Alameda Point. We help Alameda buyers and homeowners with jumbo purchase loans, refinances, equity lines and reverse mortgages. In the Alameda market, a pre-qualification based on a phone conversation is not enough. Listing agents want to see that a lender has reviewed pay stubs, tax returns, bank statements and credit, and that the buyer is approved subject only to the property. That is what a PNL pre-approval delivers.
Get Pre-approved
Housing ranges from Victorian and Craftsman homes in the Gold Coast, Fernside and the East End to 1960s and 70s homes on Bay Farm Island and Harbor Bay, with condos and townhomes along South Shore, the West End and the new Alameda Point and Marina Village developments. The pre-approval process for Alameda buyers starts online or by phone, with no credit pull at the first step. Once we talk through your goals, we collect documents through a secure portal, review the file and issue a letter, usually within one to two business days. Letters are updated for each offer you write.
Alameda buyers who are a few months from being ready can still start the pre-approval conversation. We review the credit report, point out what would improve the score or the debt ratio, and set a target date. Starting early often turns a marginal file into a strong one by the time the right home comes on the market.
From Gold Coast, Fernside, East End, West End to the edges of Alameda, we have closed loans on the kinds of homes and lots that are typical of the East Bay. Alameda is roughly two hours west of our Gold River office, so our clients there handle the whole loan by phone, email and secure e-signature without ever needing to make the drive.
Questions about home loan pre-approval in Alameda are what we do all day. Reach Pacific National Lending at (916) 526-2700, or start online and we will call you back with specifics rather than a sales pitch.
Get Pre-approvedLearn more about the program itself: Home Loan Pre-Approval · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of Oakland Estuary bridges, September 2024" by Pi.1415926535, CC BY-SA 4.0.
A pre-qualification is an estimate based on what you tell a lender, usually without documents or a credit check. A pre-approval means the lender has reviewed your actual pay stubs, tax returns, bank statements and credit report and approved you subject to the property. Sellers and agents in Alameda give far more weight to the second, and so do we.
Most lenders treat the credit report and income documents as valid for roughly 90 to 120 days, depending on the lender and program. If your search in Alameda runs longer, we update the file with current pay stubs and statements and refresh the letter. Updating is routine and does not restart the process from the beginning.
Once your documents are uploaded, a loan officer usually completes the review and issues the letter within one to two business days, sometimes the same day for straightforward files. Gathering the documents is what takes most Alameda buyers the longest. Self-employed borrowers or buyers with multiple income sources may need a little more time for the review.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.