
Alameda is an island city across the Oakland Estuary, reached by the Posey and Webster tubes, the Park Street and Fruitvale bridges and a ferry to San Francisco, and it is known for its Victorian homes, the Park Street and Webster Street shopping districts and the redeveloping former Naval Air Station at Alameda Point. We help Alameda buyers and homeowners with jumbo purchase loans, refinances, equity lines and reverse mortgages. The idea that you need 20 percent down to buy a home in Alameda keeps a lot of qualified households renting longer than they should. In practice, most purchase loans we broker close with much less. Conventional financing allows 3 percent down for qualifying buyers, FHA requires 3.5 percent, and VA and USDA permit zero down for borrowers who meet their eligibility rules. Pacific National Lending lines these programs up for Alameda buyers, explains how each one treats mortgage insurance, and recommends the structure that leaves you with the lowest total cost rather than just the smallest check at closing.
Call Pacific National Lending for low down payment mortgages in Alameda: (916) 526-2700
Get Pre-approved
Most Alameda purchases land in jumbo territory, and the buyers are usually two-income households who want a quieter, flatter alternative to Oakland or San Francisco with a ferry or tube commute. Older homes here often need a lender who is comfortable with foundation, pest and dry-rot findings, so we structure the pre-approval around the actual property, and we compare conventional, jumbo and VA options for every file rather than defaulting to one program. Conventional 3 percent down programs like HomeReady and Home Possible offer reduced mortgage insurance for moderate-income Alameda buyers, and standard conventional loans allow 3 to 5 percent down with private mortgage insurance that can be canceled once you reach 20 percent equity.
Get Pre-approved
Housing ranges from Victorian and Craftsman homes in the Gold Coast, Fernside and the East End to 1960s and 70s homes on Bay Farm Island and Harbor Bay, with condos and townhomes along South Shore, the West End and the new Alameda Point and Marina Village developments. Low down payment buyers in Alameda often ask whether they should drain savings to put down a little more. Sometimes a few extra percent moves you into a cheaper mortgage insurance tier and pays for itself quickly, and sometimes it simply leaves you with no cushion for a broken water heater or a slow month at work. Pacific National Lending models both paths next to each other. We also look at seller-paid closing costs, lender credits and gift funds, since each one changes how much of your own money has to show up at the closing table in Alameda.
First-time buyers in Alameda can often layer CalHFA's MyHome assistance or local programs on top of a low down payment loan, reducing cash to close even further. We check eligibility for every buyer who might qualify.
We help borrowers with low down payment mortgages throughout Alameda, including Gold Coast, Fernside, East End, West End, and across the East Bay. Alameda is roughly two hours west of our Gold River office, so our clients there handle the whole loan by phone, email and secure e-signature without ever needing to make the drive.
If you are weighing low down payment mortgages in Alameda, send us the basics through the form below or call (916) 526-2700. You will get a straight answer about what you qualify for and what it would cost, with nothing pulled on your credit until you say so.
Get Pre-approvedLearn more about the program itself: Low Down Payment Mortgage · All loan options · Purchase · Refinance · Today's rates
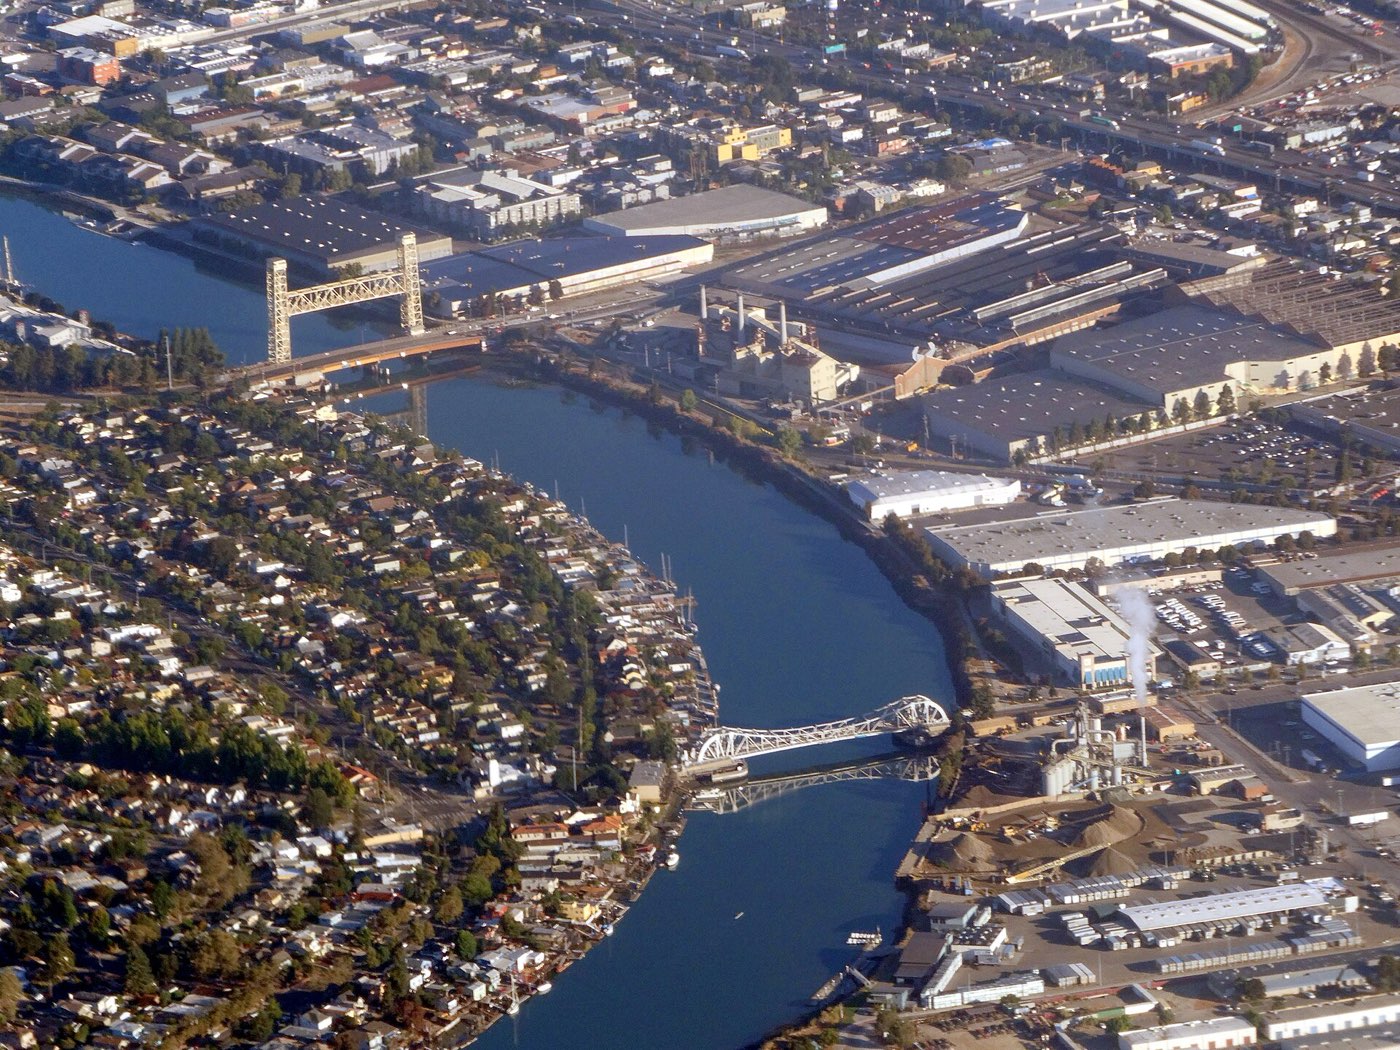
Area photo: "Aerial view of Oakland Estuary bridges, September 2024" by Pi.1415926535, CC BY-SA 4.0.
Two main programs allow zero down: VA loans for eligible veterans, active-duty service members and some surviving spouses, and USDA loans for homes in qualifying rural and suburban areas with household income under the program limit. Whether a specific Alameda address qualifies for USDA depends on the current eligibility map. Beyond those, down payment assistance layered on an FHA or conventional loan can bring a Alameda buyer's own contribution close to zero, depending on the program.
Usually yes, for two reasons: the loan balance is larger, and mortgage insurance is added until it can be removed. How much more depends on the program, your credit score and the lender. Conventional PMI can drop off as equity builds, while FHA insurance often remains for the life of the loan unless you refinance. Pacific National Lending shows Alameda buyers the payment for each program so the difference is clear before you decide.
Yes, on most programs. Conventional, FHA and VA loans allow gift funds from family members and certain other donors for the down payment and closing costs, though each program has its own rules about who can give and how the transfer is documented. The donor signs a gift letter and the lender traces the funds. We tell Alameda buyers exactly what paperwork to gather so the gift does not slow down underwriting.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.