
Most Alameda purchases land in jumbo territory, and the buyers are usually two-income households who want a quieter, flatter alternative to Oakland or San Francisco with a ferry or tube commute. Older homes here often need a lender who is comfortable with foundation, pest and dry-rot findings, so we structure the pre-approval around the actual property, and we compare conventional, jumbo and VA options for every file rather than defaulting to one program. Homeowners in Alameda who are 62 or older often have more wealth in their house than in any account, and a reverse mortgage is one way to put that equity to work without selling or taking on a monthly payment. The borrower stays on title, continues living in the home and remains responsible for property taxes, homeowners insurance and maintenance. Pacific National Lending spends as much time explaining what a reverse mortgage does not do as what it does, because an informed decision is the only kind worth making in Alameda.
Call Pacific National Lending for a reverse mortgage in Alameda: (916) 526-2700
Get Pre-approved
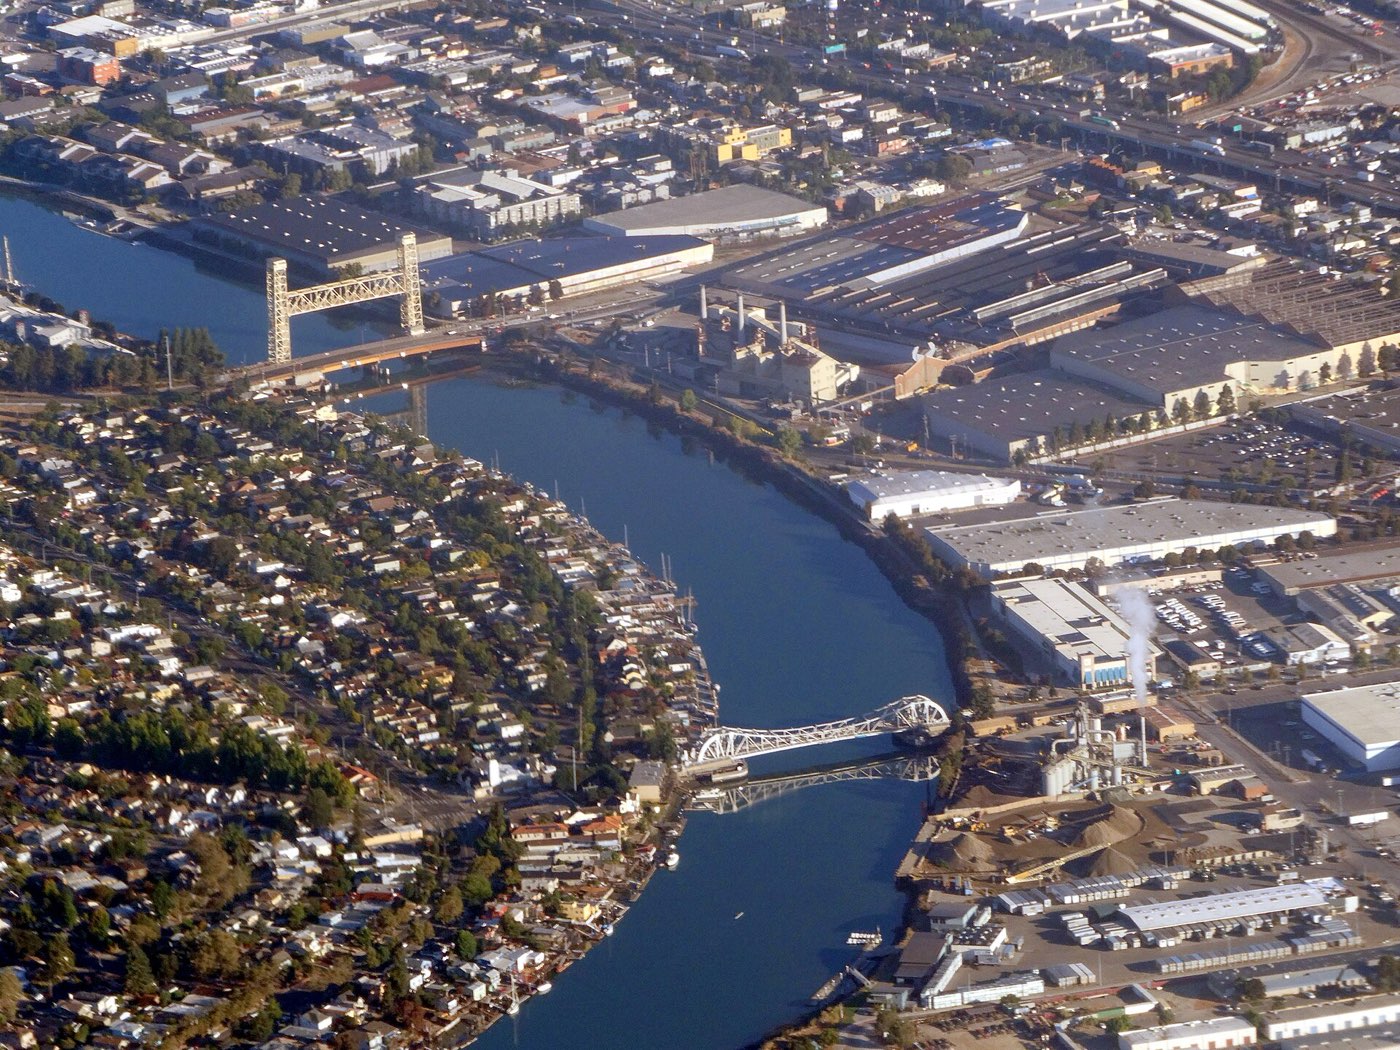
Alameda is an island city across the Oakland Estuary, reached by the Posey and Webster tubes, the Park Street and Fruitvale bridges and a ferry to San Francisco, and it is known for its Victorian homes, the Park Street and Webster Street shopping districts and the redeveloping former Naval Air Station at Alameda Point. We help Alameda buyers and homeowners with jumbo purchase loans, refinances, equity lines and reverse mortgages. A reverse mortgage is a non-recourse loan: neither you nor your heirs will ever owe more than the home is worth when it is sold. Heirs can keep the home by paying off the balance or refinancing, or sell it and keep any remaining equity. We explain these outcomes clearly to every Alameda family.
Get Pre-approved
Housing ranges from Victorian and Craftsman homes in the Gold Coast, Fernside and the East End to 1960s and 70s homes on Bay Farm Island and Harbor Bay, with condos and townhomes along South Shore, the West End and the new Alameda Point and Marina Village developments. Our reverse mortgage process in Alameda begins with an honest conversation about whether it is the right tool, and sometimes it is not. If a reverse mortgage fits, we help schedule the required HUD counseling session, order the appraisal and guide you through closing, usually in four to six weeks.
A HECM line of credit in Alameda has a feature many homeowners do not expect: the unused portion grows each year at the same rate charged on the loan, so a line opened at 65 can be considerably larger at 75. Some retirees open the line early and leave it untouched as a hedge against medical costs or a down market, drawing only if the need arises.
From Gold Coast, Fernside, East End, West End to the edges of Alameda, we have closed loans on the kinds of homes and lots that are typical of the East Bay. Alameda is roughly two hours west of our Gold River office, so our clients there handle the whole loan by phone, email and secure e-signature without ever needing to make the drive.
For a reverse mortgage in Alameda, call Pacific National Lending at (916) 526-2700 or use the secure application on this page. A licensed loan officer will follow up within one business day.
Get Pre-approvedLearn more about the program itself: Reverse Mortgage · All loan options · Purchase · Refinance · Today's rates
Area photo: "Aerial view of Oakland Estuary bridges, September 2024" by Pi.1415926535, CC BY-SA 4.0.
For the FHA-insured HECM, every borrower must be at least 62. A spouse who is younger can be listed as an eligible non-borrowing spouse and may remain in the Alameda home after the borrower passes, provided the loan terms are met. Some proprietary reverse mortgage programs accept borrowers as young as 55, but availability and terms vary by lender, so ask us which programs currently serve California.
Costs include an upfront FHA mortgage insurance premium on a HECM, lender origination charges, an appraisal, title and escrow fees and the counseling session. Most of these can be paid from loan proceeds rather than out of pocket. Interest and ongoing insurance accrue on the balance over time. The total depends on the lender, the program and the Alameda home's value, and we provide an itemized estimate so you can compare it against alternatives like a HELOC or downsizing.
The loan does not require monthly principal and interest payments, so it cannot go into default for missing those. It can become due if the borrower stops living in the Alameda home as a primary residence, lets property taxes or homeowners insurance lapse, or allows the property to fall into serious disrepair. Lenders can set aside funds for taxes and insurance at closing to reduce that risk, and we review each obligation carefully before anyone signs.
© 2026 Pacific National Lending. All rights reserved. Equal Housing Lender, NMLS #115924, DRE #01778208. Website by 1 Stop Link. Images and icons are original, licensed or free from pexels.com, unsplash.com, vecteezy.com, fontawesome.com and other platforms. Logos, seals and emblems shown do not imply affiliation with their owners.